When governments restrict foreign buyers, investors should pay attention – not panic

Every few years, headlines appear announcing new restrictions on foreign property buyers. Governments present these measures as housing protections. Critics call them barriers to investment. But experienced investors tend to interpret them differently.

Historically, governments do not intervene heavily in weak real estate markets. They intervene when demand is strong, prices are rising, and international interest reaches levels that create political pressure. In other words, restrictions are often a consequence of success, not failure.

Across Europe and beyond, we are seeing this pattern play out again — and understanding it is essential for investors evaluating residency and property opportunities today.

The pattern behind policy change

Markets tend to move through a predictable cycle.

Foreign capital enters because pricing is attractive, the legal framework is stable, and lifestyle factors are compelling. Demand rises. Development accelerates. Property values strengthen. Eventually, housing affordability becomes a domestic political issue, and governments respond with new rules.

This is exactly what has happened across several major investment destinations.

Portugal restructured its program after years of strong demand. Spain moved to dismantle its real-estate-linked residency route amid political pressure on housing. Greece raised investment thresholds significantly in key areas to manage accelerating demand rather than close the door entirely. Outside Europe, Canada introduced restrictions on foreign residential purchases after affordability debates intensified in its largest cities.

The message is consistent: governments react once a market has already proven attractive to global investors.

What history quietly confirms

When we place these cases side by side, the sequence is clear:

  • International investors enter early
  • Property demand grows rapidly
  • Prices rise and development accelerates
  • Housing becomes politically sensitive
  • Governments adjust rules or raise entry thresholds

This is not a sign that foreign investment failed. It is often evidence that it worked too well.

For investors, this insight matters because policy shifts usually lag behind market realities. By the time restrictions appear, the strongest growth phase has often already begun.

The investors’ question in 2026

If Portugal has recalibrated, Spain has stepped back, and Greece has raised thresholds, investors naturally ask:

Where in Europe does a structured, predictable pathway still exist — and where is the next phase of growth likely to occur?

This is where Cyprus becomes strategically relevant.

Cyprus: The missing piece in the cycle

Cyprus has historically lagged behind EU markets such as Greece and Portugal in terms of headline-driven investor momentum. A major reason has been structural rather than economic: Cyprus has remained outside the Schengen area, meaning that residency did not carry the same travel perception as programs in Schengen countries.

That is now changing.

The Cypriot government has publicly stated its objective for Schengen accession and has confirmed major technical preparations aimed at joining. The European Commission has also expressed support for Cyprus’ entry, with ongoing evaluations and technical work advancing toward accession.

This development is significant because it changes how international investors evaluate Cyprus permanently — not just as a lifestyle destination, but as part of the broader European mobility framework.

In simple terms, while other markets are tightening after reaching maturity, Cyprus is entering a new phase of integration.

Why This matters for the Cyprus Permanent Residency Program

If we look at the lifecycle of investment migration programs across Europe, momentum typically accelerates when three conditions align:

  • Strong EU positioning
  • Clear legal and regulatory structure
  • Enhanced mobility or perceived access across Europe

Cyprus already offers the first two. Schengen accession adds a powerful third element that investors have historically associated with other leading programs.

This helps explain why the Cyprus permanent residency route has previously moved more slowly compared to Greece or Portugal. Those markets benefited early from Schengen perception. Cyprus is now approaching the same moment — but at a time when many alternative programs are becoming more restrictive.

From an investment perspective, that timing matters.

Reading the real signal

When governments tighten investment programs elsewhere, it often confirms that demand for EU-based real estate remains strong. Investors are not abandoning Europe — they are reallocating attention toward markets that still offer clarity and opportunity.

Cyprus today sits at a unique intersection:

  • Competing markets are becoming more restrictive
  • European integration is deepening through Schengen preparations
  • The property market remains comparatively accessible
  • The residency framework remains clear and stable

Historically, this combination tends to attract early movers before broader market recognition catches up.

The strategic view forward

Policy changes across Europe tell a consistent story. Markets that successfully attract global capital eventually face political pressure and regulatory tightening.

Portugal evolved. Spain paused. Greece raised thresholds.

Cyprus, however, is entering a different stage — one defined not by restriction, but by deeper European integration and increasing international attention.

For investors, this is less about reacting to headlines and more about understanding market cycles. The strongest opportunities often exist not in markets already at peak popularity, but in those approaching their next structural shift.

Closing perspective

When governments start limiting foreign buyers, it usually means the market has already proven its appeal.

Seen through that lens, recent European policy changes are not warnings — they are indicators of continuing demand for stable, lifestyle-driven, EU real estate.

Cyprus now stands at a pivotal moment. While other jurisdictions recalibrate after years of growth, Cyprus is preparing for a new chapter — one that could redefine how international investors view its residency and property market.

For globally mobile families and entrepreneurs, timing remains everything. History shows that once attention shifts decisively, rules often follow. The opportunity tends to belong to those who understand the cycle before it becomes obvious.

The content of this article is intended to provide a general guide to the subject matter. Specialist advice should be sought about your specific circumstances.

About the author

Charles Savva is the founder and Managing Director of Savva & Associates, and is based in Nicosia, Cyprus. He is Canadian-Cypriot and has lived in Cyprus since 2001.
Bill seeks to protect guarantors of property loans

A draft bill aimed at giving stronger protection to guarantors of property loans has been put before the Plenary of the House of Representatives by DIKO MPs Zacharias Koulias and Christos Orphanides.

The bill states that lenders must first use all their legal rights against the main borrower and the mortgaged property before taking any action against a guarantor.

Using all legal options first

The main goal of the bill is clear: if a mortgage lender does not use the rights given under the Transfer and Mortgage of Immovable Property Law, they cannot turn to the guarantor.

Under the proposal, lenders must complete every step linked to the sale of the mortgaged property before pursuing a guarantor. This includes:

  • Getting a court judgment against the main borrower
  • Selling all secured assets
  • Completing the foreclosure or sale of the mortgaged property

Only after these steps are finished would a lender be permitted to take action against a guarantor.

Limiting guarantors liability after a sale

The bill also states that if a mortgaged property is used as security for a loan with guarantors, and that property is sold or taken over by the lender, the guarantor will only be responsible for the main amount set out in the guarantee agreement.

If this limit is not clearly written in the original loan agreement, or if the loan is linked to a current account approved by the guarantor, extra protections will apply. In such cases:

  • The money raised from the sale of the property, or
  • The amount paid by the lender to buy the property

must be deducted, along with any instalments already paid by the main borrower.

Tackling financial pressure on guarantors

MPs say the changes are needed because many people are trapped in loans or credit facilities taken out by others.

As a consequence, guarantors may face:

  • Loss of basic rights
  • Risk to their personal property
  • Lower borrowing ability
  • Difficulty getting loans for themselves

MPs argue that guarantors usually gain no financial benefit from the guarantees they give. At the same time, they are in a weaker position than banks, credit institutions and vulture funds.

They also point out that guarantors can be exploited. Even after secured assets have been sold (and sometimes after the guaranteed amount has been fully repaid) guarantors may still remain tied to the debt.

Possible implications for the property market

If passed, the bill could change how loan enforcement works in the Cyprus property market. Lenders would have to focus first on the borrower and the mortgaged property before turning to guarantors.

This could give more confidence to people asked to act as a guarantor in property deals. However, it would also place stricter obligations on banks and credit-buying companies operating in Cyprus.

The proposal is likely to spark debate in both the financial and real estate sectors in the weeks ahead.

Non-performing loans now worse than 2013 crisis

Cyprus’ non-performing loans have climbed beyond levels seen at the height of the 2013 financial crisis, intensifying political pressure for sweeping foreclosure reform ahead of May’s parliamentary elections.

Confidential data from the Central Bank of Cyprus reveals that total non-performing loans now stand at more than €25 billion, well above the roughly €15 billion peak recorded in 2013. The figures underscore mounting stress within the property-linked credit system, even as commercial banks have significantly reduced their direct exposure.

Vulture funds have acquired 141,478 Cypriot loans with a face value of €3.2 billion at a 20% discount. While they have since collected €5.7 billion including €3.6 billion in cash repayments, €619 million from property recoveries and €1.5 billion via debt-for-property swaps and the portfolios they hold have ballooned to €18.5 billion as interest and compound interest continue to accrue.

The government is increasingly concerned about the issue, particularly the continued application of compound interest on distressed debt.

State-owned asset manager KEDIPES, which absorbed 77,561 former co-operative bank loans worth €7.5 billion, reported an outstanding balance of €5.7 billion in June 2025, of which €5 billion remains non-performing.

Within the core banking system, the picture appears more stable. As of last June, 24,736 NPLs worth €1.45 billion remained on bank balance sheets, down €86 million since December 2024. Politically, this matters: with banks having offloaded much of their bad debt, parties argue that reforming foreclosure rules now poses less systemic risk than it would have in 2013.

One of the 30 legislative proposals set to be discussed on 9 March is thought to be from Marios Garoyian of DEPA. He proposes suspending foreclosures on primary residences valued up to €350,000 until year-end, alongside binding rulings from the Financial Commissioner and tighter caps on accrued interest.

With non-performing loans exceeding the crisis-era highs, Cyprus’ property and lending framework faces its most consequential legislative test in more than a decade.

Sharp rise in sub-€350k primary homes sold at auction

Recent figures from the Central Bank of Cyprus point to a sharp rise in the number of primary residences valued below €350,000 being sold at auction, underlining mounting pressure on middle-income households at risk of losing their homes.

Confidential quarterly data submitted to the House of Representatives and obtained by StockWatch show a growing share of non-performing loans tied to first homes in this price bracket are now ending in foreclosure.

Suspension lifted, auction numbers climb

The trend appears to have intensified since early 2024, when the suspension on foreclosures of primary residences valued up to €350,000 was lifted following earlier legislative and executive pressure.

According to Central Bank data, 98 primary residences were auctioned in the third quarter of 2025. Of these, 93 were valued below €350,000, while just five exceeded that figure.

From the 93 lower-value homes:

  • 16 were sold to third parties
  • 77 were acquired by the mortgage lender six months after the first auction process concluded

Among the 16 homes sold to third parties, eight were disposed of following a failed first auction, four at the first auction and four at the second. Of the five higher-value homes, four were taken over by the mortgage lender and one sold at first auction.

By comparison, in the third quarter of 2024 only five primary residences were sold at auction, rising to six in the fourth quarter. The latest figures therefore represent a more than twofold annual increase.

Over 800 homes on track for auction

As of Q3 2025 (July–September), more than 800 primary residences were in the foreclosure pipeline, the majority valued under €350,000. Representatives of affected borrowers say the figure continues to rise month by month.

During the same quarter, auction-stage notifications (Type IA notices) were issued for:

  • 174 properties under €350,000
  • 34 properties above €350,000

Under the Transfer and Mortgage of Immovable Property Law, a Type IA notice sets the date, time and place of the public auction and must be served at least 30 days prior to sale.

In total, 731 borrowers with homes under €350,000 and 81 borrowers with higher-value properties received notices at various foreclosure stages during the quarter.

Earlier-stage Type I notices, which signal intent to sell and granting a 45-day repayment window,  were served on 388 borrowers with properties under €350,000 and 32 with higher-value homes.

Meanwhile, 167 borrowers with homes under €350,000 and 15 above that threshold received Type Theta notices, marking loan arrears exceeding 120 days and triggering the initial foreclosure phase. From this stage, the process to auction typically spans four to six months, though legal objections and restructuring efforts can slow proceedings.

Political scramble ahead of elections

Legislation passed in late 2023 providing for a specialised court jurisdiction to hear foreclosure cases remains inactive. At the same time, the remit of the Financial Ombudsman was expanded to allow more borrowers to seek out-of-court restructuring, although decisions are not binding.

With parliamentary elections approaching, MPs are calling for a temporary freeze on foreclosures while new regulations are explored in cooperation with the government. Around 30 legislative proposals are set to be discussed before the House Finance Committee on 9 March, in the presence of the Finance Minister and the Central Bank Governor.

Based on the latest data, however, the foreclosure wave appears to be gathering pace rather than easing – signalling a critical juncture for Cyprus’ mid-market housing segment.

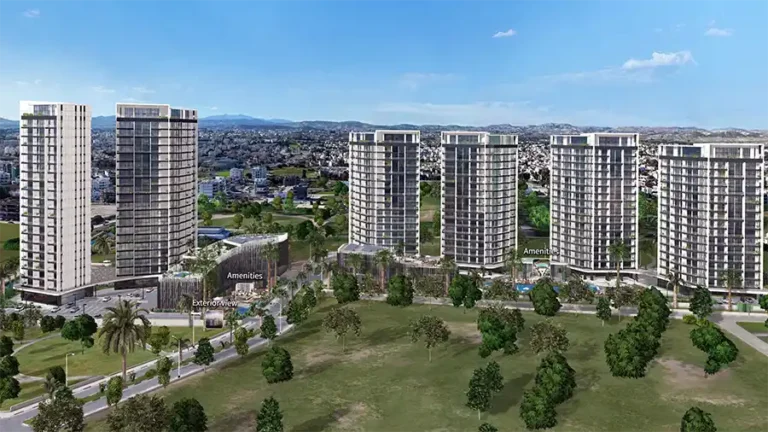
Horizon towers planned to transform Larnaca skyline

A landmark mixed-use development is moving forward in Larnaca, as Shajwawi Lebovich Karekla Developments Ltd unveils plans for six high-rise residential towers under the project name Horizon Towers.

The proposal, detailed in two Environmental Impact Assessment Studies submitted to the Department of Environment, forms part of the broader regeneration of the former petroleum refinery and LPG storage area.

Designed as a unified architectural and functional project, the development is divided into two main sections – Plot 1 and Plot 2 – with separate planning applications.

Plot 1: Twin 20-storey towers and annex 1

Plot 1 will feature two 20-storey residential towers, Horizon 1 and Horizon 2, each reaching 86 metres in height with a total of 99 apartments. A five-storey multi-purpose building, Annex 1, will include retail outlets, dining areas, a gym, wellness facilities and office space.

Residents will have access to a 550 sq m swimming pool, playground, landscaped green areas totalling 575 sqm. and public green protection zones of 6,591 sqm. The section also incorporates parking for cars and bicycles, alongside an internal road network.

Plot 2: Four towers, 427 parking spaces

Plot 2 will feature four additional apartment towers. Three 17-storey towers (Horizon 3, 4 and 5), each 75 metres high, providing 85 apartments/tower, while the 16-storey Horizon 6 will reach 70 metres and house 77 units. In total, Plot 2 comprises 332 apartments.

Amenities include two large swimming pools (900 sqm. each), a children’s pool, a 300 sqm. outdoor refreshment area, a padel court, 2,900 sqm. of green space and 427 parking spaces, including 33 for persons with disabilities.

Once completed, the six towers are set to reshape Larnaca’s skyline, signalling a new era for the city’s long-awaited waterfront regeneration.

Legal service appeals acquittals in ‘Golden Passport’ case

The Legal Service has filed an appeal against the acquittal of former House President Dimitris Syllouris and ex-MP Christakis Giovani by the Criminal Court of Nicosia in the ‘Golden Passport’ case.

The announcement was made during a press conference, marking the beginning of a second legal chapter in a case associated with the island’s high-profile “golden passport” scandal, a controversy that had significant repercussions for Cyprus’ citizenship-by-investment programme and its property market.

According to the Legal Service, the 170-page majority decision contains judicial errors which, in the view of the Prosecution Authority, warrant review by the Court of Appeal.

Speaking at the press briefing, the Head of the Service’s Communications Team, Polina Efthivoulou, confirmed that the appeal will focus on specific legal and evidentiary issues raised in the Criminal Court’s ruling.

Senior State Attorneys Andreas Aristides and Christiana Kytheraiotou were also present.

Ms Efthivoulou stressed that judicial decisions are fully respected. However, she underlined that both the Constitution and criminal procedure laws provide for an appeal mechanism where legal errors are identified.

Among the issues cited were:

  • The evaluation of witnesses who were not called to testify
  • Interpretative legal questions arising from the court’s reasoning

The Prosecution’s arguments will now be developed before the Court of Appeal, while the acquitted defendants retain full rights to contest the appeal.

Split decision in court

Particular emphasis was placed on the fact that the Criminal Court ruling was not unanimous.

Senior District Judge Maria Loizou considered that the two defendants should have been found guilty on the third charge, relating to influence peddling.

The bench of the Criminal Court of Nicosia comprised President Nikolaos Georgiades and Senior District Judges Maria Loizou and Nagia Oikonomou.

Why the Al Jazeera video was not submitted

Responding to questions regarding the footage broadcast by Al Jazeera (below), Ms Efthivoulou explained that the material had been delivered in unedited form and was examined by investigative authorities.

However, for evidence to be admissible in court, it must satisfy strict legal requirements. If a piece of evidence is deemed to be the product of an unlawful act, it cannot be accepted as testimony.

For that reason, individuals who participated in the recorded conversations were called as witnesses, rather than submitting the audiovisual material itself as evidence.

The video was a follow up of an earlier Al Jazeera report, which listed a number of dubious individuals who had been granted citizenship.

The appeal

The filing of the appeal now transfers the case to the Court of Appeal, where the legal issues raised by the Prosecution will be examined afresh.

The case continues to attract political and institutional scrutiny, particularly given its wider implications for Cyprus’ former ‘Golden Passport’ scheme; an investment scheme that resulted in significant foreign investment in the island’s luxury property market before being ‘irrevocably terminated’ amid international criticism from the EU, who launched infringement proceedings against Cyprus.

Golden Passport inquiry

Former Supreme Court judge, Myron Nikolatos, headed an official inquiry into the island’s disgraced Golden Passport scheme in August 2020.

The damning report by the interim inquiry found that citizenship had been unlawfully granted in 51.81 per cent of the cases examined, while others had shortcomings.

It seems incredible that, despite a damning report and multiple investigations, not a single individual has been held criminally accountable for the corruption and abuse surrounding the disgraced Golden Passport scheme.