Bank of Cyprus ashamed over past practices

Bank-of-Cyprus-HQTHE Bank of Cyprus new management said it feels ashamed over the bank’s past lending practices that brought Cyprus’ largest lender at the brink of collapse.

As part of the €10 billion bailout financial assistance programme for Cyprus, 47.5% of deposits over €100,000 in BoC have been converted to capital to plug a nearly €4 billion capital shortfall until 2015 on the basis of a due diligence exercise carried out by Pimco.

Furthermore, BoC absorbed the good part of Cyprus Popular Bank, the island’s second largest lender which will be wound down. The previous Board of Directors as well the Bank’s senior management, resigned under heavy criticism.

Amid soaring non-performing loans (NPLs), notably among large companies in the housing sector, the bank posted a €1.8 billion loss for the first six months of 2013, with NPLs reaching 36% of the bank’s gross loans.

“We are ashamed over the past mistakes and vow as the new Board to do our utmost not to repeat these mistakes ever again,” Christis Hassapis, the new BoC President said during an Annual General Meeting, noting “we apologise to the country, we apologise to our shareholders and we apologise to our depositors.”

Both Hassapis and the bank’s new CEO, Irish John Patrick Hourican vowed that the new board will work to regain the clients confidence and underlined the need to tackle the rising NPL’s, which is currently the bank’s major challenge.

They both made clear that the lending policy from here on will focus on the borrower’s capacity to repay its loan and not on the basis of collateral value, which was the main practice in the past.

“Lending policies and practises are being revised and the imprudent lending policy based on collateral value will be replaced with the prudent lending on the basis of the proven repayment capacity, pursuant to the supervising authority’s directives,” Hassapis noted.

On his part Hourican, who worked in Royal Bank of Scotland before assuming the top management seat in BoC, said the board will make small steps to regain the people’s confidence. “However, it will take time, as there is no quick fix to the bank’s problems,” he said.

According to Hassapis, the bank is currently implementing a restructuring plan, featuring a specialized management of the bank’s large exposure to land developers and a centralized handling of the NPLs in a bid to achieve their swift recovery or restructure as far as of viable corporations are concerned.

Hourican said following the bailout decisions, BoC became hostage to the Cypriot economy.

“A deeper and more prolonged contraction with its consequences on unemployment, real estate and client confidence could derail the implementation of the restructuring plan,” he said, noting “perhaps our biggest task at hand is regaining the confidence of our clients.”

However, he described the CBC’s new directive on NPLs as “foolish as it traps large amount of capital,” and he added the tendency of asset quality deterioration will continue beyond the first half of 2013.

Noting that the bank is working to contain this tendency, Hourican stressed that there is no problem with the bank’s capital.

According to the latest financial results, BoC capital adequacy ratio stands at 10.7% whereas the IMF believes that BoC’s Core Tier 1 capital ratio will remain at 9% throughout the programme period, that is, until 2016.

Source: Cyprus News Agency

Central Bank issues stark warning on foreclosures

central bank of cyprusACCORDING to reports, the Central Bank of Cyprus has warned banks to change their attitude towards borrowers and avoid foreclosing on their primary residences in cases where they are unable to maintain their mortgage repayments.
The Central Bank has also called on banks to help borrowers rework their mortgages and even went as far as giving notice that there could be a haircut on non-performing loans in efforts to facilitate their repayment.

A special team of Central Bank officials has been set up to check the practice of the Bank of Cyprus before carrying out similar checks at other lenders.

A source at the Central Bank said that the thirty largest borrowers have bank debts totalling €6 billion and that priority will be given to the seizure and sale of their property.

Standard & Poor’s raises Cyprus rating as risks recede

STANDARD & Poor’s raised its long-term sovereign debt rating on Cyprus to B- from CCC+ on Friday, saying immediate risks to debt repayments on the bailed-out Mediterranean nation appeared to have receded.

“The stable outlook reflects our view of the implementation risks that remain as the end of the three-year European Commission, International Monetary Fund, and European Central Bank program approaches, balanced against the upside potential we see coming from Cyprus’ economy,” S&P said in a statement.

It is the first ratings upgrade in three years for Cyprus, which was shut out of international financial markets for high implied yields on its traded debt in May 2011 and came to the brink of financial collapse earlier this year. Fitch rates Cyprus B-, and Moody’s Investors’ Service at Caa3.

The island, one of the smallest countries in the euro zone, signed up to a 10 billion euro bailout program with the IMF and EU in March.

Program money was not allocated to commercial banks, and the accord was conditional on Cyprus shutting down a major bank and recapitalizing a second lender with its clients’ deposits.

Lenders have since reviewed Cyprus’ progress twice, giving it positive reviews.

Standard and Poor’s said the biggest challenge in Cyprus meeting lenders’ conditions was a privatization program, expected to raise 1.4 billion euros by 2018.

An upside risk to the economy was anticipated revenue from offshore gas finds, but commercial incentives could be thwarted by the island’s political division between Greek and Turkish Cypriots, Standard and Poor’s said.

Cypriot president Nicos Anastasiades, a conservative who took power just before the bailout was concluded in March, said his government would be “consistent and disciplined” in managing the island’s adjustment.

“This is the result of painful sacrifices by our people, but also the decisive policies this government has followed the past eight months,” he said in a statement.

– Reuters

Title Deeds issued at last for Froiber Group buyers

CHRIS Iacovides, the liquidator of six out of the eight companies in the Froiber Group, has successfully completed all necessary procedures for the Title Deeds to be issued by the Land Registry for a number of the Group’s apartment buildings, and his focus now is to work towards the issuing of the remainder.

“There has been much press recently regarding alleged demands from buyers by the Liquidator, on behalf of mortgagees,” said Mr. Iacovides “and the time has come to set things straight. Whilst buyers have my sympathy, they must understand that a financial institution which has funded a project and enjoys security against a specific asset is legally entitled to demand money against that security and to refuse to consent to the transfer of shares/Title Deeds, without some financial compensation.”

“I suggest that those who exert pressure and unfair criticism should take a look at the terms of the Memorandum of Understanding between the Republic of Cyprus and the Eurogroup, in relation to the residential property market and the regulation of real estate and be concerned with how close we are to property repossessions.”

Having set out his position, Mr Iacovides moved on to discuss the efforts made to issue Title Deeds for the Group companies, namely:

A&G  Property Wise Development Ltd (“A&G”)

A&G was wound up and a Court Order was made ratifying Mr Iacovides’ appointment as Liquidator on 10 May 2010. A&G’s assets are comprised of nine apartment buildings and seven houses.  There are approximately 110 buyers who purchased their property between 2002 and 2008. Recently, Title Deeds have been issued for four apartment buildings.

The other three Group companies were voluntarily wound up on 9 October 2010 and Mr Iacovides was appointed Liquidator by the members and creditors in their respective meetings.

George Andreou Developers Ltd (“George Andreou”)

George Andreou developed three apartment buildings and there were 34 buyers during the same period as mentioned above. Recently Title Deeds have been issued for all three apartment buildings.

Ktimatiki Epiloyis Ltd (“KE”)

KE developed two apartment buildings. There are a total of 10 purchasers who bought their apartments between 1999 to 2005. Separate Title Deeds have been issued for one of the apartment buildings.

Froiber Land Developers Ltd (“FLD”)

FLD’s assets are comprised of two apartment buildings, one of which is part completed. Recently, USB bank approved finance of €350,000 for the completion of the said building and the Liquidator is close to commencing the relevant works.  In total there are 14 buyers who purchased between 2002 and 2006. Title Deeds have not been issued for FLD’s properties and efforts are ongoing.

The Liquidator made it abundantly clear that in order for the transfer of shares of land and/or Title Deeds to be possible, purchasers will be asked to pay various financial institutions, mainly banks, which enjoy security through their mortgages, the Inland Revenue Department for taxes due, as well as sewerage charges, municipal taxes and more. The amounts are calculated proportionally based on the size (m2) of each apartment.

“Unfortunately, the Group does not have other assets beyond what is set out above which could be realised with a view to settling the companies’ liabilities.”

Mr Iacovides explained that during the last 3 years many efforts have been undertaken to facilitate the issuing of the Title Deeds and added that this would not have been possible without the full understanding of the Director of the Inland Revenue and his officers, whom we thank.

“We had a series of meetings and exchanged much correspondence with officers of the Inland Revenue regarding tax matters. Additionally, financial statements for the liquidated companies were prepared and submitted to the Department.”

“Many apartment buildings contained irregularities,” he added, “we therefore submitted statements of intent for the purposes of the town planning amnesty. Following a review of each file by the planning authority and the issuing of the certificate of final approval these were filed with the Land Registry in order for it to issue the separate Title Deeds.”

There are still several files with the Planning Authority for the granting of the certificate of final approval, concluded Mr. Iacovides.

Finally, Mr Iacovides stated that the philosophy of CRI is simple, “We won’t make a drama out of a crisis”, nevertheless, he would like to make it clear that abusive and inappropriate behaviour by buyers towards managers of his office will not be tolerated.

Title Deeds, Mr Anastasiades

NOW that the over-rated Anastasiades-Eroglu coffee afternoon has come and gone, perhaps it is time we returned to some state of normalcy and took a serious look at core issues that have dogged our society, the economy and the perception that Cyprus has in other people’s minds.

Of course, the biggest thorn is the Title Deeds fiasco, that, despite promises from all Interior ministers and Attorney Generals, remains unresolved. Our Risk Watch columnist Alan Waring raised the issue in an appropriately timed article last week. Even the dreaded Troikans attempted to have a go at the issue, but will probably fall flat on their faces as they, too, couldn’t care less about the home buyers who have been duped by crooks, both in the property sector and within the banks.

Here, we have to make a clear definition of ‘home buyer’ rather than ‘property buyer’ for two reasons:

  1. the right to a home is enshrined in EU law, whereas the right to a property is not, and
  2. we are talking primarily here about people who stand to lose the homes they live in – few are property investors in the commercial sense.

With all the name calling regarding major property developers (Aristo, Leptos, Shacolas) piling up unsecured loans and creating a black hole within Bank of Cyprus of about €1 billion euros, perhaps it is time we also started to name and shame the head honchos at Alpha Bank, Bank of Cyprus, USB and possibly ex-Laiki Popular, who, logically, must be the accountable persons at the bank who have dished out the now non-performing loans or have knowingly allowed developers to get away with murder.

But as with all else in Cyprus, nothing will happen unless President Anastasiades grasps the importance of this problem, which his predecessors had ignored.

There is a whole issue about how we tend to use impersonal language as if ‘the banks’, ‘the government’ etc. are amorphous, inanimate monoliths. There are flesh-and-blood monsters – sociopaths probably – who do all these appalling things and it is time we should start using the names of those ultimately responsible and accountable, even if they personally did not ‘pull the trigger’.

There is the general point about anonymity masking accountability and the specific issue of these banks rapaciously going after innocent home buyers who were never party to their developer’s mortgages or the latter’s defaults. Even if they personally did not mastermind and operate these ‘white collar terrorist activities’, the past chairmen and general managers of the above-mentioned banks must have been aware of them and no doubt had to authorise them, while the present executive leadership cannot claim ignorance.

Quite apart from the moral degeneracy, there is the short, medium and long-term damage this fiasco will do to the Cyprus property sector and the overall economy. After this, who will ever trust a Cyprus bank again? Foreign investors in all sectors are now much more aware of what is going on here – and they do not like it.

Title Deeds Mr Anastasiades

UK to assist Cyprus on title deed delays

UK to help Cyprus with Title Deed delays
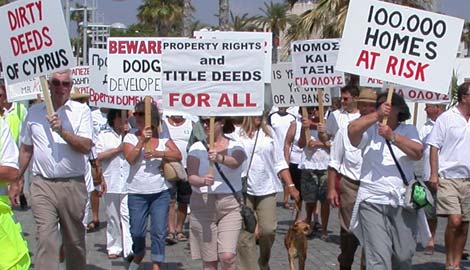
Protesters outside the Bank of Cyprus in Paphos (CPAG)

THE British High Commission yesterday welcomed a government initiative to coordinate efforts to resolve title deeds problem facing British home buyers here.

“We welcome the Cypriot Government’s plans to work towards a solution to the property issues that so many UK and Cypriot nationals face,” a spokesperson told The Cyprus Daily yesterday.

“And we are grateful for the steps the government has taken so far.

The UK continues to support and offer assistance to the government in their efforts to tackle property issues,” it added.

Cabinet’s decision came at the proposal of the Foreign Minister to tackle property buyers’ complaints against the Republic of Cyprus.

Many British home buyers have complained about failure by Cypriot developers to issue title deeds.

The Cabinet proposal includes cooperation between a ministerial committee to be set up for this purpose- and representatives of ministries and government services with the High Commission.

The High Commission yesterday confirmed there was “an on-going programme of exchange of expertise between the UK and Cyprus on wide range of issues.”

“The UK, will of course, continue to offer assistance to the Cypriot government to help tackle the many property issues faced by homeowners of all nationalities in Cyprus.

“The High Commission will continue to raise concerns with the Cypriot government including at Ministerial level and we continue to work together to find a solution,” it added.

The Commission encourages anyone experiencing problems with property to seek legal advice by engaging an independent lawyer who will be best placed to advise on rights and methods of redress.

The Interior Ministry is responsible for coordinating the cooperation with the High Commission but Reform Commissioner Emmanuella Lambrianides will be responsible for amending the law and monitoring property market issues.

UK to assist on title deed delays