Israeli-linked Cyprus developments raise planning questions

0

Three different Israeli-linked developments have made headlines in Cyprus in recent months. Each has raised questions about planning or environmental approvals, site selection and the impact of development on the surrounding area.

In Latchi, a major hotel complex reached the final stages of completion while key licensing issues were still unresolved. In Trozena, an almost deserted village in Limassol district became the focus of an ambitious revival plan backed by an Israeli-linked investor. The project had already made significant progress when authorities found that the required permits had not been secured.

In Polemidia, meanwhile, plans for a Jewish school for up to 1,500 pupils are being advanced in an area already facing serious traffic and planning pressures. The local municipality has complained that it was not even asked for its views on the development, while earthworks had already begun on the site.

Taken together, the three cases could be seen as examples of a familiar problem in Cyprus: development moving faster than the planning system.

Build first, ask for permission later

The hotel development at the former Elia Latchi/Zening Hotel Eco Resort was the subject of an investigation by Kathimerini. It found that construction had progressed, and in some areas was completed, despite delays and outstanding building and planning permits.

The investigation also highlighted unauthorised additions, including a third floor and other facilities. Instructions to stop work and demolish unapproved additions were reportedly ignored. Subsequent decisions and administrative handling effectively allowed the owner to regularise or legalise the deviations.

The case was particularly striking because Iraklis Achniotis, former director of Licensing at the Paphos District Local Government Organisation, reportedly refused for months to sign off the building permit despite pressure to bring the matter to a close.

His position was based on the fact that the owner had continued construction and completed the hotel while breaching the planning framework. Significant unauthorised structures and other irregularities on the site were still outstanding.

That raises a basic question for any planning system: what is the value of a permit if a developer can build first and resolve the paperwork later?

Trozena: regeneration versus environmental protection

The Trozena project presents a more complex picture.

The village was abandoned decades ago. The investment plan includes 60 homes based on the restoration of old properties, tourism facilities, a camping site and a winery.
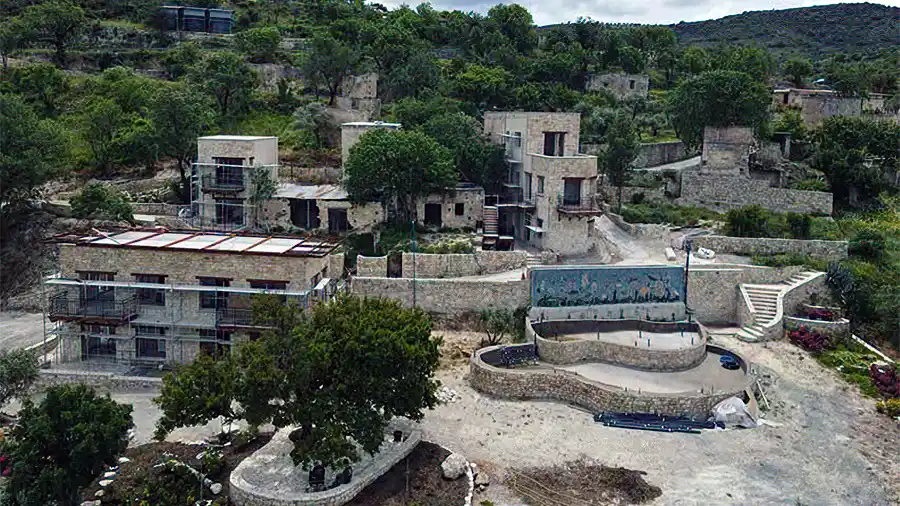
Israeli-linked property development in Trozena, Cyprus
Photo credit: Cyprus Mail – Works in the village of Trozena

Earthworks and other interventions were carried out in the area, along with extensive heavy construction work, while planning applications were still under review. The Department of Environment and the Limassol District Local Government Organisation subsequently called for an overall master plan and for work requiring permission to be suspended.

The issue is even more sensitive because the area is linked to the Natura 2000 network.

Environmental groups have alleged land filling, tree cutting and work affecting a riverbed. They have also raised the possibility that the interventions may be linked to the drying up of the well-known Trozena waterfalls.

That last claim remains an allegation rather than an established causal link. But this is precisely why the sequence matters. Environmental assessment is meant to come before intervention, not to explain afterwards how the consequences of work already carried out should be managed.

There is also a strong argument in favour of the investment from local stakeholders. They say it could bring economic activity and infrastructure back to a place that has been abandoned, while helping a wider area that has suffered from decline.

That argument cannot simply be dismissed. But it does not answer the central question: why should construction come before the necessary permits and rules?

Polemidia school raises planning concerns

The Polemidia project is one of the largest private education investments in Cyprus in recent years.

Originally presented as the Cyprus Jewish Academy of Excellence and now promoted by the Yael Foundation as Yael Private School of Limassol, the project is worth more than €50 million. It is planned for up to 1,500 pupils and is intended to open in 2027.

The project is led by Rabbi Yehoshua Smukler, an educator with extensive experience running Jewish schools and a long professional career in Australia. He has described the new school as a future “cornerstone” of Cyprus’ Jewish community, arguing that it will make the island even more attractive as a place to live for members of the community.
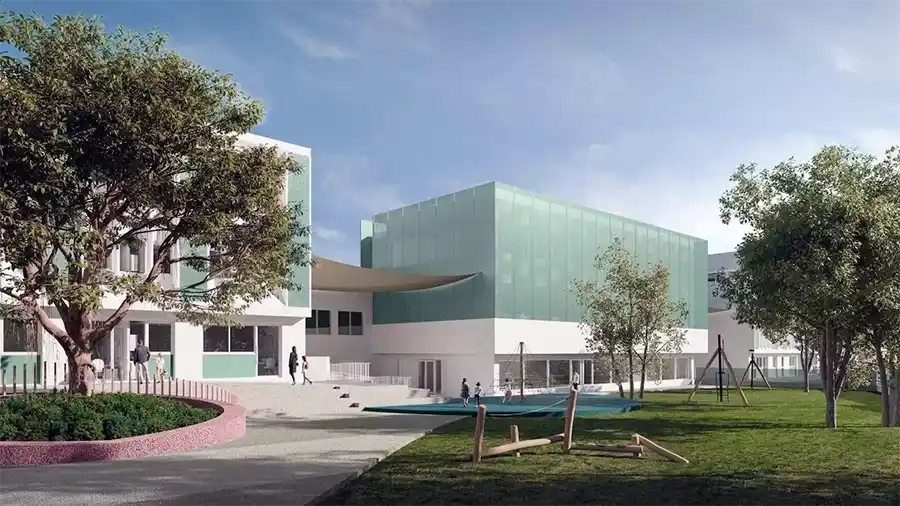
Photo credit: Phileleftheros – Jewish school worth €50 million for Polemidia

Smukler has spoken of a small but rapidly growing Jewish community in Cyprus, which he estimated at about 4,000 families. The vision is for the school to become more than an educational institution. It is intended to be a focal point for Jewish life on the island.

Here, the objections have mainly been about planning, location and infrastructure.

The Polemidia municipality has raised concerns that such a large development will add to traffic congestion and put further pressure on local infrastructure. It has also complained that the project was decided without consultation with the municipality.

“Instead,” municipal secretary Yiannakis Kallikas told StockWatch on 15 May 2025, “the company has fenced off the site and earthworks have begun.”

The statement inevitably brings the issue back to licensing, where an interesting contradiction emerges.

In February 2025, Israeli media were already presenting the project as a confirmed development. Journalists were shown around the site and heavy machinery was already operating there.

Yet on 7 February 2025, the Ministry of Education said that no application had yet been submitted to establish the school.

The ministry also made clear that Cyprus law does not permit an exclusively religious school in the sense of requiring pupils to follow specific religious teaching. The statement came in response to the way the project had been presented by its own promoters.

By May 2025, the picture had changed. Reports said the architectural plans and application to the Ministry of Education were being completed, while sources close to the foundation viewed the ministry’s position as positive.

The outstanding approval matters because no private school can operate in Cyprus without the approval of the Minister of Education. Among other requirements, this includes planning and building permits for use of the premises as a school, a final approval certificate, suitability and fire-safety certificates, and approval of the educational programme.

In October 2025, the Ministry of Finance included the Cyprus Jewish Academy of Excellence on its list of major investment projects under way or being planned in Cyprus.

The project appeared in the ministry’s Macroeconomic Outlook presentation under “Major investment projects”. Its timetable stated that the architectural plans and the application for approval of the private school by the Ministry of Education were being completed.

In other words, as late as October 2025, the Ministry of Finance was still describing the school’s licensing application as a process nearing completion.

There has been no publicly identified announcement confirming that the Ministry of Education’s licensing process for Yael Private School has since been completed.

What can be confirmed is that, on 10 July 2026, the business name “YAEL PRIVATE SCHOOL PRIMARY” was registered with the Registrar of Companies. Its registered address is 1 Filias Street, Polemidia, and its owner is THE PRIVATE SCHOOL YAEL LTD.

That registration is a commercial-name registration. It is not, by itself, an operating licence for a private school from the Ministry of Education.

There is another detail that raises questions. According to the Polemidia municipal secretary, the municipality had previously sought to create a sports centre on the site but was unable to secure permission for such a project.

Is there a question of “soft settlement”?

The three cases could, in isolation, be viewed as episodes of the familiar Cypriot disorder in planning and other areas of public administration.

But they have emerged at a time when the growing Israeli presence in Cyprus, particularly in property and major developments, has triggered a wider social and political debate.

That presence is becoming more visible and, above all, more permanent. New infrastructure is being created to serve a community that is not simply investing or holidaying on the island, but is increasingly establishing and organising parts of its life here.

This debate cannot be ignored. Nor should it slide into easy generalisations.

It is in this context that references to “Israeli penetration” and even “soft settlement” have begun to appear. Such descriptions should not be adopted without careful evidence.

The risk of exaggeration is especially high while the conflict in the Middle East continues to make public debate politically and emotionally charged.

It would be wrong to demonise the Israeli presence. It would also be wrong to dismiss every concern as prejudice, xenophobia or, more seriously, antisemitism.

There are legitimate issues beneath the public unease: rapidly growing economic and social activity, strong demand for property at a time of housing pressure, foreign ownership of land and developments that raise questions about whether investors receive preferential treatment.

Those issues are sufficient to justify serious political debate.

Cyprus and Israel: the bigger property question

Israeli presence in Cyprus has clearly increased in recent years. So too has concern that the change is no longer limited to isolated voices.

The property market is perhaps the most visible sign.

Israeli buyers are among the most important groups of foreign purchasers, particularly in Larnaca, Limassol and Paphos. This is happening while affordable housing is becoming increasingly difficult for Cypriots to access.

That does not mean foreign demand is the only cause of rising prices. It is not.

But the debate becomes more serious when it turns to how much land is changing hands, which strategic areas are being acquired and which parts of the country are becoming concentrated in foreign ownership.

At the same time, the creation of businesses and facilities serving a growing Israeli and Jewish community reinforces the impression of a presence that is no longer simply investment or tourism.

It is taking on elements of settlement and permanence.

That has prompted concerns about changes to the character of some areas and the emergence of more closed communities. Those concerns deserve scrutiny, without assuming that the outcome is necessarily negative.

Larnaca may be the clearest example of this change.

For decades, the city felt it was lagging behind Limassol and Paphos. It has now attracted greater investment, more construction, new businesses and a much stronger international presence.

Israeli demand has contributed to that transformation. Its positive effect on the local economy cannot be ignored.

But success also creates pressure.

When demand for property rises much faster than supply, prices follow. When new families settle permanently, they naturally create demand for schools, places of worship, businesses and community facilities.

The result is not necessarily negative. But it is a real social change, and social change cannot be left entirely to market forces.

The state’s responsibility

Ultimately, the greatest responsibility lies with the state.

Cyprus has learned to measure the success of investment in millions of euros, companies, tourists and jobs. It is less clear that it has learned to measure it with the same care in square metres of land, ownership concentration, pressure on housing costs, strain on infrastructure and changes to the character of particular communities.

An investment can be good for GDP while making housing less affordable.

It can increase the value of an existing property while putting it further out of reach for a younger buyer. It can create jobs while placing new pressure on local infrastructure.

There is no contradiction in that. There are different interests that the state must balance.

Cyprus needs foreign capital, businesses, expertise and people who will settle here and create economic activity.

But an open economy does not mean an unprotected state. Nor does a business-friendly investment climate mean flexible rules that change according to the size or nationality of the investor.

The test should be simple and consistent: the same planning, environmental and licensing rules must apply to everyone.

If society begins to believe that the strategic importance of the Nicosia-Tel Aviv relationship means tolerance, exceptions or a “come one, come all” approach to regulation, the damage could be serious.

It would not only weaken confidence in Cyprus’ planning system. It could also undermine public support for a bilateral relationship that Cyprus has every interest in keeping strong.

The real issue, therefore, is not whether Israeli investment is good or bad.

It is whether Cyprus has a planning and regulatory system strong enough to manage major investment fairly, transparently and in the public interest – whoever the investor may be.

(Translated from an article first published in Kathimerini)
Cyprus property market shifts as demand moves downmarket

Cyprus’ property market suffered a sharp fall in the second quarter, but the figures do not point to a complete freeze. Sales of new-build apartments and houses fell by 42.2% compared with the first quarter. Their total value dropped by 46.6%.

Yet an analysis by Landbank Analytics, obtained by Kathimerini, suggests that buyers did not simply disappear. Instead, demand shifted towards lower- and mid-priced homes, while Nicosia gained ground and several local markets proved more resilient.

The luxury end of the market also remained active, with high-value sales recorded in areas such as Germasogeia and Pegeia.

Sales fall sharply in the second quarter

The number of contracts of sale fell to 1,317 in the second quarter, from 2,277 in the first three months of the year.

Their combined value dropped from €748.6 million to €400.1 million. That means 960 fewer contracts were recorded over the period.

The average value of each contract fell by 7.6%, from €328,762 to €303,808. The median value also declined, falling 6.3% from €240,000 to €224,850.

The lowest recorded sale rose from €42,000 to €55,000. At the other end of the market, the highest transaction fell from €13 million to €4.69 million.

Apartments saw their average value fall by 5.5% to €262,574. Their median value declined by 7.3% to €204,000.

Houses recorded a larger fall. Their average value dropped by 12.7% to €501,800, while the median fell by 10.5% to €340,000.

Buyers turn towards more affordable homes

The biggest change came in the lower price brackets.

Homes priced below €300,000 accounted for 68.1% of all new-build apartment and house sales in the second quarter. That was up 5.5 percentage points from the first quarter.

The €300,000 to €499,999 bracket moved in the opposite direction. Its share fell from 27.1% to 23.1%.

The strongest gain was recorded among properties priced between €150,000 and €199,999. Their share rose from 21% to 24.8%.

Homes priced between €200,000 and €299,999 also increased their share, from 27.1% to 28.2%. Properties below €150,000 recorded a smaller rise.

The figures suggest that affordability became a bigger factor in the market during the quarter.

Nicosia emerges as a stronger market

Nicosia was one of the clearest bright spots in the second quarter.

The capital’s share of all new-build apartment and house contracts rose from 26.7% to 34.5%. Its share of total transaction value increased even more, from 17.1% to 26.2%.

Average transaction value in Nicosia rose by 9.3%. The median value remained unchanged at €185,000.

Limassol remained the leading district by total sales value. However, its share fell from 40.8% to 32.4%.

Larnaca was more stable, with a median transaction value of €190,000 and a slight rise in its share of total value.

Paphos continued to have the highest median value among the districts, at €352,500. Its overall market share, however, edged lower.

Limassol leads the busiest local markets

Looking at individual areas, Limassol recorded the highest number of deposited contracts in the second quarter, with 129 transactions.

Aradippou followed with 122, while Lakatamia ranked third with 92. Paphos recorded 79 transactions.

Strovolos and Larnaca each recorded 71 transactions. Livadia and Latsia completed the top eight.

However, transaction numbers alone do not show which markets performed best during the downturn.

Lakatamia recorded the smallest fall among the busiest areas, with transactions down by 14.8%. Aradippou followed, with a 17.6% decline, while Latsia recorded a 24% fall.

That compares with a 42.2% decline across the wider market.

The figures point to a clear difference between areas. Price levels, location, property type and the balance between supply and demand may all help explain why some markets have held up better.

Some areas actually recorded growth

A small number of local markets managed to increase sales during the quarter.

Agios Dometios was one of the strongest performers. Sales of new-build apartments and houses rose by 22.6%, while the median value increased by 7.7% to €154,000.

Dali also recorded growth. Transactions rose by 15.8%, from 19 to 22, while the median value increased by 8.1% to €194,500.

The Municipality of Nicosia saw almost no change in the number of contracts, with a decline of just 4.4%. However, total transaction value rose by 31.3%.

Average transaction value in the municipality jumped by 37.4%.

Ypsonas was another relatively resilient market, with transaction numbers falling by just 9.1%.

Luxury property market remains active

The fall in overall sales did not prevent strong activity at the top end of the market.

Germasogeia recorded 43 transactions worth a combined €27.6 million in the second quarter. Its average transaction value reached €640,970, while the median stood at €400,000.

Across the first half of the year, Germasogeia recorded 132 transactions worth €89.1 million. The median transaction value was €472,500.

Potamos Germasogeias recorded even higher values. Its median transaction value reached €600,000 in the second quarter, while the average rose to €838,783.

Pegeia recorded the highest median value among areas with at least 10 transactions. Its median reached €855,000, while its average transaction value topped €1 million.

The figures show that the luxury market has not moved in line with the wider slowdown.

A market reshaped rather than frozen

The second-quarter figures paint a more complex picture than a simple market downturn.

Overall sales and values fell sharply. But demand has also shifted towards properties that are more affordable, while some districts have retained a much larger share of their activity.

Nicosia has gained market share, several areas have shown resilience and a number of local markets have even recorded higher sales.

At the same time, premium locations continue to attract buyers willing to spend large sums.

“The true appeal of an area is determined by a combination of sales volume, resilience, median value, and the types of homes it offers,” said Andreas Christoforides, Founder & CEO of Landbank Group.

For Cyprus’ property market, the second quarter therefore looks less like a broad collapse in demand and more like a period of adjustment. Buyers appear to be changing what they buy and where they buy it, with affordability playing a greater role in the market.

(Translated from an article in Kathimerini)

Cyprus housing crisis: 3,300 new homes in the pipeline

Housing has become one of Cyprus’ biggest economic and social challenges. It is now high on both the domestic and European Union political agenda, as well as a daily concern for households, particularly younger people.

Rising rents and house prices, combined with a shortage of homes in the main urban centres, have made affordable housing harder to secure. The pressure is being felt by thousands of households, young couples, students and workers.

The issue is no longer simply a matter of social policy. Housing is closely linked to the labour market, worker mobility, business competitiveness and the wider economic outlook.

Against this backdrop, the Ministry of Interior has developed a housing policy over the past two years based on two main pillars. The first is to increase the supply of homes, with a particular focus on affordable housing. The second is to improve people’s purchasing power through grants, subsidies and targeted housing schemes.

Officials at the Ministry told Economy Today that the housing problem cannot be solved through financial support alone. Nor can it be addressed simply by building more homes. Instead, action is needed on both the supply and demand sides of the market.

The Ministry also accepts that major measures aimed at increasing supply will take time to deliver. In particular, the impact of planning incentives and Build to Rent is expected to become clearer over the next two to three years, as projects now being approved or built enter the housing market.

The supply battle: 3,300 homes in the pipeline

The Ministry of Interior regards the Planning Incentives and Build – Rent schemes as its most important measures for increasing housing supply.

The schemes make use of an asset controlled by the state: development rights. These are seen as a valuable negotiating tool when working with property developers.

Under the schemes, developers can receive up to 45% additional building density. In return, some or all of the extra homes can be made available for affordable sale or rent.

Developers can also buy the additional building density. The money raised goes to the Affordable Housing Special Fund of the Cyprus Land Development Corporation (CLDC), which finances other affordable housing programmes.

The Ministry considers the schemes its biggest intervention so far to increase the housing stock. The aim is to use the value of state development rights to support the creation of new homes.

Early figures suggest strong market interest. So far, 53 applications have been submitted to use the incentives. Together, they represent more than 3,300 residential units expected to be built over the next two years.

Around 400 of those homes are expected to be offered as affordable housing. Applications involving the purchase of additional building density have already generated around €17.5 million in contributions to the CLDC’s fund.

The Ministry expects these projects to add significantly to housing supply in the coming years. In turn, this could help bring supply and demand into better balance and ease pressure on prices.

Officials say the measure is particularly important because it can create new homes without a direct cost to the state budget. Instead, it uses planning incentives to encourage private development.

CLDC returns to the heart of housing policy

The Cyprus Land Development Corporation is also taking a more prominent role in the government’s housing strategy.

The organisation had experienced a long period of limited activity because of funding constraints following the end of Cyprus’ former citizenship-by-investment programme. It is now back at the centre of affordable housing policy.

The CLDC has been given wider responsibilities and a more active role in delivering government housing policy. New sources of funding have also been secured through state support and contributions linked to other housing schemes.

The state has already allocated €16 million for the first phase of an affordable rental project in Agios Nikolaos, Limassol. Construction work has begun.

A further €12 million has been approved for the development of 54 residential units in Strovolos.

The foundation stone has also been laid for the ADONIS III project in Polemidia. It is the second major project under way in Limassol district aimed at easing housing pressure.

According to figures presented to Economy Today, the CLDC has moved from a period of inactivity between 2022 and 2024 to a much more active programme in 2026.

Projects now moving towards delivery include:

  • 244 homes for sale at affordable prices;
  • 192 homes for affordable rent; and
  • the subdivision of 135 plots in Nicosia, Larnaca, Limassol and Paphos.

The Ministry expects these projects to form a key part of Cyprus’ affordable housing policy in the years ahead.

State land to provide around 500 homes

Another major initiative will use state-owned land for housing.

The scheme was announced by the President of the Republic last December. It aims to deliver around 500 homes on state-owned plots in Nicosia, Limassol, Larnaca and Paphos.

Private developers will build the projects under a design-and-build model. The CLDC will then manage and allocate the apartments based on the social and financial criteria used by its housing programmes.

The scheme is currently at the stage of preparing the necessary studies. However, the Ministry believes it could become one of the most important sources of affordable housing in Cyprus over the next few years.

New approach to student housing

The growing student population is creating another source of pressure in the rental market.

The expansion of existing universities and the arrival of new higher education institutions have increased demand for student accommodation. The Ministry believes this has contributed to higher rents in some areas, while also creating a concentration of students in particular neighbourhoods.

The government is therefore promoting a new type of student accommodation rather than relying solely on traditional halls of residence.

The new units can contain up to 10 rooms and must be used exclusively for students. They will have lower requirements for communal areas and greater flexibility over parking.

For example, a five-room student accommodation unit could be created within just 77 square metres of usable floor space.

The model can be used for new developments or for converting existing properties. The property must be within one kilometre of a recognised higher education institution.

Housing for workers in tourism and industry

One of the newest measures is the Collective Accommodation Units scheme. It is designed to provide a lower-cost housing model for workers in key parts of the economy.

Announced at the end of 2025, the scheme is aimed mainly at employees in tourism, retail and industry.

The model uses smaller units, fewer parking spaces and fewer communal areas to reduce construction costs.

The Ministry says there is already interest, particularly from tourism businesses. It expects the scheme to ease some of the pressure on the existing housing stock by providing accommodation for workers who might otherwise compete for private rental homes.

Housing schemes available to households

Alongside measures aimed at increasing supply, the government has a number of schemes that directly support households.

These include financial assistance for renovating empty homes, grants for people moving to rural and remote areas, and support for displaced people.

Renovate – Rent

The Renovate – Rent scheme aims to bring empty or unused homes back to the rental market.

Owners of vacant properties can receive financial support to renovate or upgrade their homes. In return, the properties must be offered to eligible tenants at an affordable rent for at least four years.

The grants are:

  • €20,000 for a one-bedroom home;
  • €30,000 for a two-bedroom home; and
  • €40,000 for a three-bedroom home.

To qualify, a property must have been vacant for at least 12 months. It must also have been connected to the Electricity Authority of Cyprus network before 2012, have the necessary permits and not be rented to relatives.

So far, 81 applications have been submitted by property owners. Of these, 52 were approved and 28 rejected for various reasons.

On the tenant side, 106 applications have been received, with 59 approved.

However, interest has been below expectations. Reasons include reluctance among owners to use the scheme, higher construction material costs and a shortage of contractors able to carry out renovation work.

Rural, mountain and remote area housing

Housing schemes for rural, mountain and remote areas are among the most significant measures currently available to households.

They remain open until the end of 2027 and have a wider goal than simply helping people buy a home. They are also intended to support population growth and economic activity in areas facing demographic decline and abandonment.

The programme covers 276 communities and areas across Cyprus. These include border communities, mountain areas, disadvantaged urban areas and particularly remote communities, where the highest incentives are available.

Support can be used to build a new home, buy an existing property or buy and renovate a home. In some cases, it can also cover a property gifted by a parent or relative, provided the required upgrading work is carried out.

Financial support covers up to 50% of eligible costs. Grants range from €20,000 to €75,000, depending on the location and household composition.

Additional incentives can take the total support to as much as €95,000. This makes the programme one of the most generous housing schemes currently available in Cyprus.

Recent changes include higher grants for displaced people, extra incentives for homes in the Tylliria area and higher income limits for the most remote communities.

There is also additional support for large families and the option to combine the scheme with home energy efficiency programmes. Special provisions apply to people with disabilities and to extra construction work that may be needed because of difficult mountain terrain.

Demand remains strong. Between 2019 and the end of 2025, 2,892 applications were submitted and 2,027 were approved. Total grants were close to €77 million.

The figures suggest that rural and remote areas continue to attract households looking for more affordable housing options.

Support for displaced people

Housing programmes for displaced people also remain in place through the Service for the Care and Rehabilitation of Displaced Persons.

The schemes provide financial assistance of between €20,000 and €40,000 to buy or build a home.

They were significantly simplified in 2025, with higher income thresholds and more categories of eligible applicants.

During 2025 alone, 2,197 applications were approved, with grants worth a total of €56.4 million.

Young couples’ scheme reaches the end of its cycle

A separate scheme offering financial assistance to young people and young couples aged up to 41 has now completed its cycle.

The programme offered support of up to €50,000 and initially targeted 400 beneficiaries. Demand was strong enough for the government to extend the scheme to cover additional applications.

A total of 1,018 applications were submitted. Around 700 are expected to be approved, with total grants approaching €26 million.

Although the scheme is now closed, it represents one of the government’s most significant recent interventions to help younger households enter the housing market.

The housing challenge over the next few years

Cyprus’ current housing strategy is attempting to tackle the problem on two fronts.

The government is providing immediate support to people who need housing today while also seeking to increase the number of homes available over the longer term.

The Ministry believes that bringing thousands of new units to the market will be essential to closing the gap between supply and demand.

That means maintaining the policy over the coming years so that new developments continue to add to the available housing stock.

At the same time, the issue of empty and unused homes remains unresolved.

Officials were asked about estimates that around 30,000 homes across Cyprus may be vacant. They said that making meaningful use of these properties would require legislative changes and political decisions, including possible tax measures.

For now, the focus remains on delivering the schemes already under way. Almost €200 million has been allocated through housing measures over the past two years.

The bigger test will be whether the combination of new construction, affordable housing and targeted financial support can ease the pressure on Cyprus’ housing market.

The most significant supply measures will take time to deliver. But if the projects now in the pipeline reach the market as planned, Cyprus could see a substantial increase in its affordable housing stock over the next two to three years.

(Translated from an article in Economy Today)

Cyprus construction materials prices rise 3.33% in July

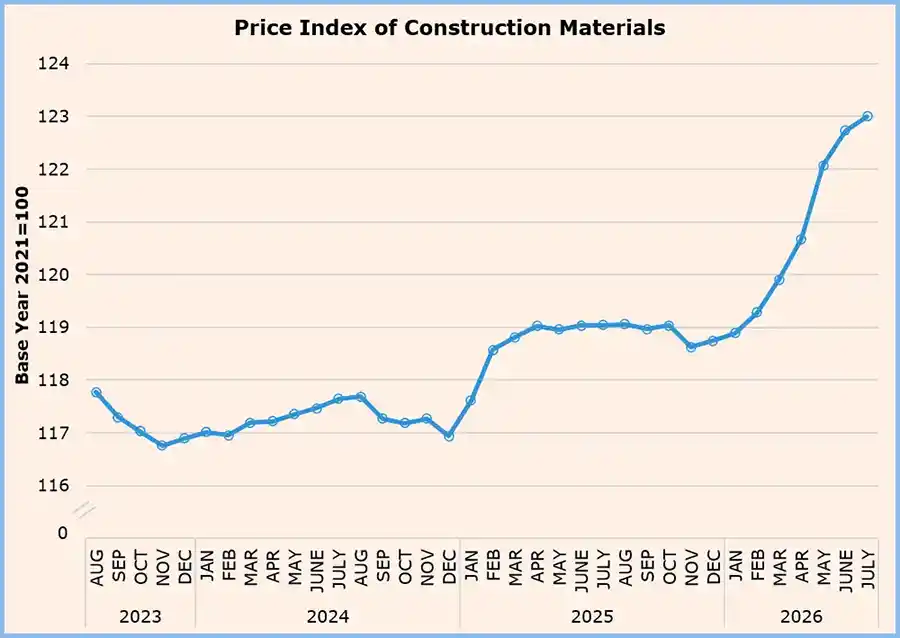
The price of construction materials in Cyprus rose by 3.33% in July 2026 compared with the same month a year earlier, according to data released by the Statistical Service on 18 August.

The Construction Materials Price Index reached 123.00 points in July, based on 2021=100. On a monthly basis, the index increased by 0.23% from June 2026.

For the first seven months of 2026, construction material prices were 1.87% higher than during the same period in 2025.

Cyprus construction materials prices July 2026

Electrical and mechanical goods lead seven-month rise

Electromechanical goods recorded the strongest increase among the main material groups between January and July, rising by 2.69%.

Wood, insulation, chemical and plastic products followed with a 2.60% increase. Metal products rose by 2.23%, while minerals recorded a 1.97% increase.

At subcategory level, electrical materials posted a 5.40% rise during the seven-month period. Plastic products increased by 4.94%, while aluminium and other metal products rose by 4.43%.

Not all material groups recorded higher prices. Ceramic products fell by 1.34%, while heating and cooling equipment declined by 1.11%.

Iron and steel products increased by 1.13%. Cement products and stone recorded rises of 1.74% and 1.51%, respectively.

Annual price increases remain strongest in electrical materials

Looking at the annual change, electrical materials recorded the largest increase, rising by 6.61% in July 2026 compared with July 2025.

Plastic products followed closely, with prices up 6.58%. Aluminium and other metal products increased by 6.14%.

Within wood, insulation, chemical and plastic products, wood products rose by 5.12% year on year. Chemical products increased by 2.80%, while insulation materials were up by 1.16%.

Metal products recorded an annual increase of 4.94%, with iron and steel products rising by 4.32%.

Mineral products also recorded higher prices. Cement products rose by 3.88%, while aggregates increased by 1.56% and stone by 1.30%.

Within mineral products, cement-based products increased by 1.20%. Ceramic products were almost unchanged, rising by just 0.23%.

The electromechanical goods category recorded an annual increase of 3.29%. Other electromechanical goods rose by 3.22%, while heating and cooling equipment fell by 1.67%.

The latest figures point to continued upward pressure on several construction inputs in Cyprus, particularly electrical, plastic and metal products. For developers and contractors, changes in material prices remain an important factor in project budgets and construction pricing.

Cyprus Renovate – Rent scheme struggles to gain momentum

The Cyprus Renovate – Rent scheme is struggling to gain traction, despite offering property owners incentives that are generally seen as attractive enough to encourage them to refurbish and rent out homes and apartments.

The scheme was announced in November 2024 and can also cover renovation work carried out up to one year before an application. Yet, as of yesterday, just 86 applications had been submitted through the Cyprus Land Development Corporation. Of these, 54 had been approved, while a further seven were still awaiting examination.

The figures suggest the scheme has yet to develop any real momentum. Its original target was to bring 1,000 residential units back into the rental market. Based on the current take-up, however, that target appears increasingly difficult to achieve.

The scheme was initially backed by a €25 million budget. Its first period of operation has now ended, but it has been renewed and will remain in force until 2027.

Why are property owners staying away?

The key question for those involved in the housing market is why so few owners are taking part. There is no single answer, but market conditions appear to be playing an important role.

According to industry estimates, owners of older residential properties can earn more by renting them to groups of foreign workers on a per-person basis. This can involve letting a property to five, 10 or more occupants at an agreed rate.

For some owners, the choice is therefore straightforward. Joining the government scheme means making an application, leaving a property vacant while renovation work is carried out and initially paying for the work themselves. The property must then be rented for four years at 70% of the market rent.

This may be particularly difficult for owners with just one residential unit. They face a lengthy process and a period without rental income, followed by a four-year commitment at a reduced rent.

Developers may have other priorities

Another question is why professional housing operators and property owners with greater financial resources are not making greater use of the scheme.

One view among market participants is that financially stronger owners are responding to high housing demand in a different way. They may prefer to build new homes and apartments, renovate existing buildings for sale, or refurbish properties and sell them at a profit.

The proceeds can then be reinvested in another project. This may be more attractive than entering a government scheme that involves an application process, a four-year rental commitment and rents below the market rate.

Is the scheme too complicated?

Some property professionals also believe that the scheme has been held back by its complexity.

The original call for applications and implementation guide ran to 34 pages and contained provisions that could be difficult for the average homeowner to understand. Several of the requirements were later simplified.

Many of the conditions were introduced for a clear reason. They were designed to prevent abuse and ensure that public funds were used for their intended purpose.

However, the safeguards may also have made the scheme harder for individual property owners to access. For a homeowner unfamiliar with housing regulations, funding rules and renovation requirements, the application process can appear daunting.

Renovate – Rent: maximum financial support

The maximum level of financial support available under the scheme is:

  • One-bedroom home: up to €20,000
  • Two-bedroom home: up to €30,000
  • Three-bedroom home: up to €40,000

On paper, these incentives can make a significant contribution towards renovation costs. The low number of applications suggests, however, that the financial support alone has not been enough to persuade large numbers of owners to participate.

Cyprus renovate-rent scheme launched to unlock empty homes

The scheme was introduced following estimates that around 30,000 residential units across Cyprus were effectively out of the market. Many were considered unsuitable for occupation because of their physical condition, appearance or other problems.

The idea was simple: bring these homes back into use through renovation, increase the supply of rental properties and, ultimately, ease pressure on rents.

The challenge is that the wider housing market has changed rapidly. According to the 2021 population and housing census, Cyprus had 492,931 residential properties. Of these, 354,818 were homes of usual residence, while 138,113 were vacant or used for temporary residence.

Some of the vacant properties are likely to be holiday homes, so the figures do not mean that all 138,113 units could readily become long-term rental properties.

Most homes in urban areas

The geographical distribution of housing also helps explain where the pressure is greatest.

Some 298,020 homes, or 60.5% of the total, were recorded in urban areas. These are also the areas where housing demand is generally strongest.

A further 194,911 homes, or 39.5%, were located in rural areas.

Nicosia district accounted for 163,350 homes, or 33.1% of the total. Limassol followed with 132,574 homes (26.9%), while Larnaca had 82,274 (16.7%), Paphos 74,473 (15.1%) and Famagusta 40,260 (8.2%).

Population growth adds to housing pressure

Cyprus had a population of 923,381 in 2021, up 9.9% from 840,407 recorded in the 2011 census. That represents an increase of 82,974 people who needed somewhere to live.

Over the same period, the number of homes increased by 59,719, or 13.8%.

Since 2021, legislation has also made it easier for companies and third-country nationals to come to Cyprus for specialised employment. This is widely seen as another factor behind rising demand for residential property.

There have also been reports of pressure on Cypriot families and students to leave rented homes and apartments so that landlords can re-let them to foreign tenants at higher rents.

The bigger housing policy question

The weak take-up of the Cyprus Renovate – Rent scheme raises questions about how government housing incentives should be designed.

The scheme offers meaningful financial support, but owners are weighing that support against renovation costs, lost rental income, administrative requirements and a four-year commitment at a below-market rent.

At the same time, strong housing demand creates other opportunities for property owners, including new development, renovation for resale and higher-yield private rentals.

For the government, the challenge is now to determine why a scheme designed to unlock thousands of unused homes has attracted so few applicants.

Unless the economics and application process become more attractive, the target of returning 1,000 homes to the rental market by 2027 could remain well out of reach.

(Translated from an article in Philenews)

Cyprus rents: housing supply must be the priority

0

Cyprus needs rental policies that do more than limit rent increases. The priority should be to increase the supply of homes available to rent, according to Yiannis Misirlis, President of the Real Estate Development Association.

He said a debate about limiting rent rises is entirely justified, particularly when a sudden increase can place significant pressure on a household budget. However, the key question is how such rules would affect the wider property market.

According to Mr Misirlis, international experience shows that limits on rent increases can provide security for existing tenants. But if such measures are too strict or remain in place for the long term, they could reduce investment in new rental housing.

There is also a risk that market activity could fall, creating two distinct groups. One would include people who have already secured a home, while the other would be made up of households looking for a new property at higher market rents.

Demand is outpacing supply

In Cyprus, the main issue is not simply rising rents. Mr Misirlis said demand has grown faster than supply in some cities and housing categories.

When many households compete for a limited number of available homes, controlling prices alone cannot create the missing housing stock.

“The best protection for a tenant is to give them more choice.”

Mr Misirlis said genuine bargaining power exists when people can choose between a larger number of suitable homes.

He stressed that this does not mean allowing a rental market without rules. The state can still provide protection against extreme or abusive practices, but such measures should be targeted and objective.

The aim, he said, should be to protect tenants without discouraging the development of new homes.

Build-to-Rent could increase supply

Mr Misirlis also called for targeted financial support for households that are genuinely struggling with housing costs. He argued that this would be preferable to broad measures covering the entire rental market.

He placed particular emphasis on creating an effective Build-to-Rent framework. This would give institutional and private investors a stronger incentive to develop homes specifically for long-term rental.

New investment that increases the available housing stock should not, he argued, be undermined by rules that weaken the investment case from the outset.

Another option is to bring empty or underused homes back into the market. Incentives for renovation and long-term letting could help unlock additional rental properties.

At the same time, planning and licensing procedures for new residential developments need to be significantly faster.

Mr Misirlis said it made little sense to express concern about a shortage of affordable homes while new developments remain tied up in the approval process for years.

Landlords also need certainty

Increasing the supply of rental homes will also require long-term renting to remain predictable and financially viable for landlords, he said.

That means effective dispute resolution, greater certainty around tenancy agreements and guarantee schemes for vulnerable tenants. Such measures could reduce risk and encourage more owners to place properties on the rental market.

The housing problem has no single cause, Mr Misirlis concluded, and cannot be solved with one measure.

A successful policy should therefore provide protection for tenants, security for landlords and, above all, more housing supply.

Its success should not be judged only by whether a rent increase was held back in the short term. The real test will be whether, five years from now, a new family has more homes to choose from at prices it can genuinely afford.

(Translated from an article by Yiannis Misirlis)