Livadia property boom transforms Larnaca’s growth landscape

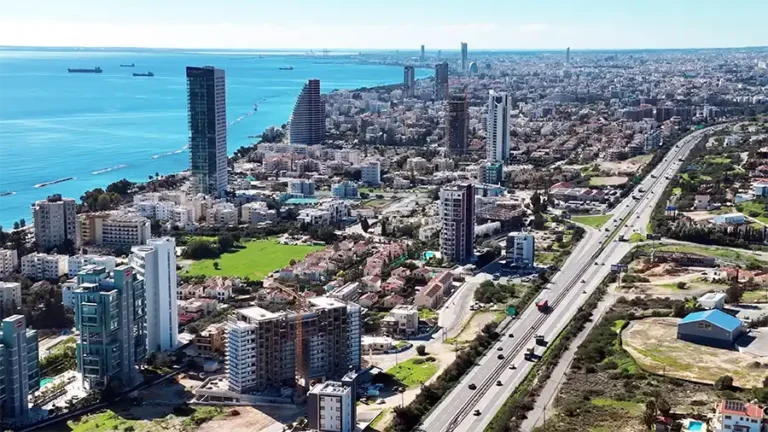
Just over two years ago, Livadia’s transformation appeared impressive. Today, it has become one of the most remarkable property stories in Cyprus.

When plans first emerged in March 2024 following the relocation of the area’s oil storage facilities, investment interest already exceeded €130 million, according to municipal figures. While strong demand was anticipated, few could have predicted the extraordinary pace of development now taking shape.

Today, projects worth hundreds of millions of euros are either under construction or progressing through the planning system. Crucially, these figures exclude the newly released three-kilometre beachfront, where future investment is expected to exceed €1 billion.

Construction activity accelerates across Livadia

The surge extends well beyond the reclaimed waterfront.

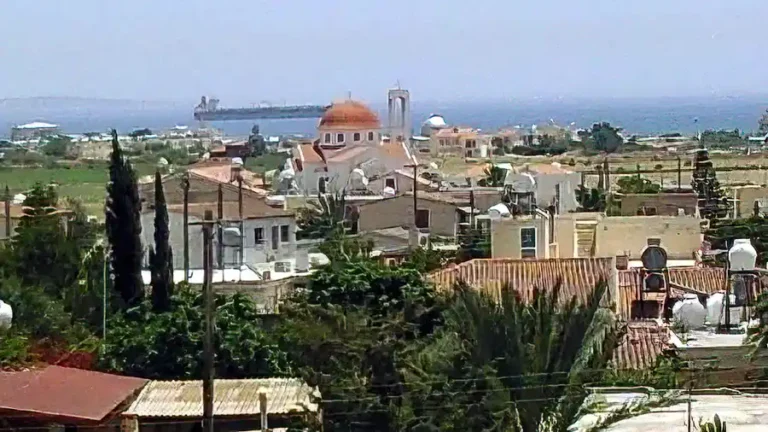
Across Livadia, now a municipal district of Larnaca, formerly undeveloped land is rapidly giving way to apartment schemes, mixed-use developments and residential complexes. Areas once characterised by reed beds are being transformed into modern neighbourhoods, while numerous additional plots have either entered construction or are awaiting planning approval.

The scale of activity represents one of the most significant periods of residential expansion Larnaca has witnessed in recent decades.

Horizon Towers set to introduce Livadia’s first high-rise skyline

Among the flagship projects is Horizon Towers, a landmark residential scheme proposed by developer SLK.

According to the Larnaca District Local Government Organisation, the €200 million development is approaching the licensing stage. The project will comprise six residential towers delivering 528 homes, marking Livadia’s first major high-rise community.

Elsewhere, several mixed-use schemes valued at tens of millions of euros are nearing completion close to the former refinery site.

International investors are playing a leading role in the area’s transformation. Israeli developers are behind many of the largest schemes, while Lebanese, Iranian and Ukrainian investors are also active. However, in terms of volume, the majority of smaller residential developments continue to be delivered by Cypriot property companies.

Planning approvals reflect surge in demand

Official figures highlight the pace of expansion.

During 2025, authorities issued 385 planning permits and 454 building permits within Livadia alone.

In the first half of 2026, a further 178 planning permits and 228 building permits were approved.

According to Angelos Hadjicharalambous, President of the Larnaca District Local Government Organisation, Livadia is currently experiencing the fastest rate of development anywhere in the district.

He said demand continues to rise, driven by a constant flow of planning applications, with most proposals focusing on apartment buildings rather than individual houses. He also confirmed that additional applications for high-rise developments have been submitted, emphasising that all projects comply with the area’s approved Local Area Plan.

Rapid growth brings growing concerns

Livadia’s population stood at 8,581 in the 2021 census.

If current construction levels continue, local officials believe the population could increase dramatically rather than simply doubling over the coming years. Horizon Towers alone could eventually accommodate several thousand residents.

The challenge is particularly striking given Livadia covers only nine square kilometres, compared with neighbouring Aradippou, which spans approximately 57 square kilometres.

Infrastructure struggles to keep pace

While investment continues to pour into the area, local authorities warn that essential infrastructure is failing to keep up.

Traffic congestion has become increasingly severe, while local schools have already reached capacity.

Deputy Mayor Marios Armenis has repeatedly called on central government to accelerate two key road projects considered critical to Livadia’s future growth.

The first is the long-delayed second phase of Alexandrou Panagouli Avenue. Despite the masterplan having been prepared as far back as 2009, construction is not expected to begin before 2028.

Armenis argues that the delay is forcing increasing volumes of traffic onto local residential roads that were never designed to accommodate such demand.

The route also serves three schools, including a secondary school, a high school and a nursery, with more than 1,000 pupils travelling through the area each day. He warned that significant road safety concerns remain unresolved and indicated that school parent associations are preparing to take action ahead of the next academic year unless improvements are made.

A second priority is Andreas Mouzakis Street, which local officials describe as unsafe due to the absence of pavements despite heavy pedestrian use. The road provides access to the Anorthosis stadium, nearby retail facilities and residential areas, while congestion during peak hours has become a major concern.

Public projects aim to preserve Livadia’s character

Alongside private investment, several public regeneration projects are reshaping Livadia’s traditional centre.

The first phase of the €3 million reconstruction of Makarios Avenue is scheduled for completion in early 2027, with a second phase expected approximately one year later.

Plans are also progressing to redevelop the village square surrounding the Basket Weaving Memory Museum.

Meanwhile, the first phase of a €4 million flood channel enhancement project has been completed, creating a pedestrian connection between Livadia and the Larnaca–Dhekelia coastal road.

Further improvements include landscaping works at the Agios Savvas roundabout and the refurbishment of 12 public parks, several of which now feature basketball and tennis courts.

Looking ahead, plans are being prepared for a new regional primary school, kindergarten and environmental park, with funding expected to be sought through European programmes.

Balancing growth with identity

Livadia’s transformation is reshaping not only Larnaca’s property market but also the wider residential landscape of Cyprus.

For local leaders, however, the challenge extends beyond accommodating record levels of investment. Maintaining the area’s identity while ensuring infrastructure keeps pace with population growth will ultimately determine whether one of Cyprus’ most ambitious development stories becomes a long-term success.

From billion-euro waterfront ambitions to hundreds of new homes already under way, Livadia is rapidly becoming one of the country’s defining real estate investment destinations.
Cyprus property market remains stable as buyer trends shift

The Cyprus property market remained broadly stable during the first half of 2026, although significant differences emerged between regions, property types and buyer budgets, according to the latest market analysis from Ask Wire.

A total of 8,313 residential property transactions were completed during the first six months of the year, with a combined value of approximately €2.31 billion.

The figures include 2,580 house sales worth €932 million and 5,733 apartment transactions with a total value of €1.38 billion.

While overall activity remains healthy, Ask Wire says the key question for the market is no longer whether demand exists, but where buyers are concentrating their spending, which price brackets remain affordable and whether available housing stock matches current demand.

Limassol records highest transaction value

Limassol remained Cyprus’ most valuable residential market, recording 2,216 transactions worth a combined €823 million.

However, average transaction values declined compared with 2025.

The average house sale fell to €392,000, down from €452,000, while the average apartment transaction decreased to €363,000 from €400,000.

According to Ask Wire, strong sales volumes should not be interpreted as evidence that all asking prices remain achievable. Instead, buyer demand appears to be shifting towards lower overall transaction values, reflecting greater price sensitivity.

Nicosia driven by local demand

Nicosia recorded 2,167 residential transactions with a combined value of €421 million.

House sales are running approximately 15% ahead of the pace recorded in 2025, although the average house value declined to €224,000 from €247,000.

Apartment transaction volumes remained broadly unchanged, but the average apartment price increased to €183,000, compared with €169,000 a year earlier.

Ask Wire says the capital’s housing market continues to be supported primarily by local buyers using mortgage finance, with affordability remaining the dominant factor influencing purchasing decisions.

Larnaca apartments dominate the market

Larnaca completed 1,944 residential transactions worth €365 million during the first half of the year.

Apartments accounted for the majority of activity, with 1,521 transactions at an average value of €171,000.

House sales, meanwhile, were around 13% lower than during the same period in 2025.

The analysis suggests demand continues to be driven by first-time buyers, domestic investors and purchasers seeking more affordable alternatives to Limassol.

Paphos maintains demand for premium homes

Paphos recorded 1,614 residential property transactions with a combined value of €618 million.

Although house sales were slightly below last year’s pace, average house values increased significantly to €535,000, compared with €470,000 in 2025.

Ask Wire says demand for higher-value properties remains resilient, although it is concentrated in specific locations and targeted developments that appeal to well-defined buyer groups.

Famagusta requires a more cautious pricing strategy

Famagusta recorded 372 residential transactions worth a total of €84 million.

House sales were noticeably weaker than during the first half of 2025, while the average apartment transaction stood at around €150,000.

According to Ask Wire, current market conditions require a more conservative approach to pricing, sales expectations and absorption rates, particularly outside the province’s strongest coastal locations.

Cyprus property market outlook

The first-half data suggests that Cyprus’ residential property market remains fundamentally stable, but buyers are becoming increasingly selective.

Affordability continues to shape purchasing decisions in the domestic market, while premium properties remain in demand only where location and product quality justify higher prices.

Rather than experiencing a broad-based slowdown, the market is becoming more segmented, with regional dynamics and realistic pricing playing an increasingly important role in determining sales performance.

Cyprus property prices threaten financial stability

Cyprus property prices continue to represent one of the biggest risks to the country’s financial stability, according to the Central Bank of Cyprus (CBC), which has warned that persistent growth in the real estate market is increasing the banking sector’s exposure to a potential market correction.

In its Financial Stability Report 2025, the Central Bank identifies rising property values as one of the most significant domestic risks facing the financial system, alongside geopolitical tensions, volatility in international financial markets and vulnerabilities linked to growing global public debt.

Banks remain heavily exposed to the Cyprus property market

Although Cyprus’ banking sector demonstrated resilience throughout 2025, the report says important vulnerabilities remain because banks continue to hold substantial portfolios of loans secured against real estate.

The Central Bank notes that property collateral provides an important safeguard against borrower defaults. However, it cautions that the banking system’s heavy dependence on real estate leaves it vulnerable should Cyprus property prices experience a significant correction.

The report adds that this risk is amplified by continued price growth and long-standing structural weaknesses within the property market.

Close monitoring of property market risks

The report dedicates a separate section to the financial sector’s exposure to real estate, highlighting the importance of closely monitoring developments across the Cyprus property market.

The Central Bank says existing macroprudential measures remain in place for residential mortgages and other secured lending. These include limits on the:

  • Loan-to-Value (LTV) ratio
  • Debt Service-to-Income (DSTI) ratio

According to the regulator, these safeguards are designed to contain credit risk and preserve the quality of banks’ loan portfolios.

Capital buffers maintained to strengthen resilience

As part of its strategy to reinforce the banking system, the Central Bank confirmed it has maintained the Countercyclical Capital Buffer (CCyB) at 1.5%.

The measure is intended to ensure banks retain sufficient capital reserves to absorb losses if economic conditions deteriorate or loan defaults increase.

Banking sector enters 2026 from a position of strength

Despite its warnings over Cyprus property prices, the Central Bank says the country’s banking sector entered 2026 with strong capital adequacy and high liquidity levels.

The report also highlights a further improvement in asset quality, with the ratio of non-performing loans falling to a historic low of 1.6%.

However, policymakers stress that the close relationship between banks and the real estate sector means vigilance remains essential. A significant decline in property prices could reduce the value of collateral backing loans and ultimately undermine financial stability.

While the sector is considerably stronger than in previous years, the Central Bank concludes that continued monitoring of the Cyprus property prices and the wider real estate market will remain critical to safeguarding Cyprus’ financial system.

Cyprus top property sales hit €286.4m in first half of 2026

The combined value of the 50 most expensive property transactions completed in Cyprus during the first half of 2026 reached €286.4 million, according to data analysed by property intelligence platform Ask Wire.

The ten largest transactions alone accounted for €161.7 million, highlighting the continued concentration of high-value investment activity in the island’s premium real estate market.

€55 million Limassol deal tops the market

The largest transaction recorded between January and June involved the sale of agricultural land with an existing building in Moni, Limassol district, for €55 million, making it the most valuable property deal completed during the period.

Of the ten biggest transactions nationwide, six were completed in Limassol, with a combined value of €117.2 million. Paphos followed with three deals worth €35.5 million, while Larnaca recorded one transaction valued at €9 million.

Limassol continues to lead Cyprus property investment

Limassol retained its position as Cyprus’s dominant high-value property market across the broader list of the 50 largest transactions.

The district’s ten most valuable sales totalled €148.2 million, representing 51.7% of the combined value of the country’s top 50 property transactions.

Paphos ranked second, with its ten largest deals exceeding €68.8 million, accounting for 24% of the total value.

Elsewhere, the ten largest transactions in Nicosia reached €26.7 million, while the free Famagusta district recorded €21.4 million, narrowly ahead of Larnaca’s €21.2 million.

Land dominates high-value transactions

According to Ask Wire Chief Executive Officer Pavlos Loizou, land acquisitions continued to dominate the upper end of the market, with seven of the ten most expensive transactions involving fields or development plots.

He said these assets are likely to represent prime development opportunities, potentially earmarked for luxury residential schemes or hotel projects.

Loizou also noted growing demand for office accommodation, reflecting the continued arrival of international companies establishing operations in Cyprus in recent years.

Geopolitical uncertainty slowed activity

Loizou added that eight of the ten largest transactions were completed during the first quarter of 2026, suggesting that investment activity slowed during the second quarter.

He attributed this trend to uncertainty arising from the ongoing conflict in the Middle East, which he said influenced investor decision-making during the latter part of the reporting period.

The 10 most expensive property sales in the first half of 2026

No Property Type Sale Price District / Municipality – Community
1 Agricultural fields with a building €55 million Limassol / Moni
2 Agricultural field €19.3 million Limassol / Parekklisia
3 Plot of land €14.5 million Limassol / Potamos Germasogeias
4 Apartment €13 million Paphos / Kato Paphos
5 Agricultural fields €13 million Paphos / Pegeia
6 Offices €10.7 million Limassol / Agios Athanasios
7 Agricultural field €9.5 million Paphos / Pegeia
8 Plot of land €9 million Larnaca / Chrysopolitissa
9 Agricultural field €8.9 million Limassol / Potamos Germasogeias
10 Offices €8.8 million Limassol / Agios Athanasios

Source: Department of Lands and Surveys, Analysis: Ask Wire

Cyprus property market: No housing bubble, economists say

0

Rising property sales and a sharp increase in construction activity have reignited debate over whether the Cyprus property market is heading towards overheating. However, leading economists argue that current evidence does not point to the formation of a housing bubble.

Property transactions increased by 15% during the first half of 2026, while the total floor area of licensed construction projects rose by 40% in the first quarter, prompting questions over the sustainability of the market’s rapid growth.

Speaking to news outlet StockWatch, three economists agreed that the latest figures reflect robust market fundamentals rather than speculative excess. Nevertheless, they warned that housing affordability is becoming the country’s most pressing real estate challenge.

Strong fundamentals continue to support demand

Former banker and Fiscal Council member Marios Clerides, Marios Kapnisis, Senior Manager, Deal Advisory at KPMG and property specialist, and economist Panayiotis Agisilaou, Director of Trojan Economics and lecturer at the Open University of Cyprus, all attributed the market’s resilience to long-term structural drivers.

While none believes Cyprus is experiencing a property bubble, they agreed that developments should continue to be monitored closely.

Population growth is driving genuine housing demand

According to Clerides, the current market differs significantly from previous speculative cycles because demand is being driven by demographic changes rather than excessive borrowing.

Cyprus has experienced substantial population growth in recent years, fuelled both by local demand and by the arrival of foreign professionals and employees relocating with international companies operating on the island.

He noted that housing needs vary considerably across different population groups, while in cities such as Limassol, property prices have risen to levels that are increasingly beyond the reach of many local buyers.

Assessing whether a market is overheating, he argued, cannot be based solely on transaction volumes or construction activity.

Instead, demographic trends, land availability, household investment behaviour and wider economic conditions must all be considered.

Low savings returns continue to favour property investment

Clerides also highlighted the impact of persistently low deposit rates across the eurozone.

With bank savings offering limited returns, many households continue to view real estate as an attractive investment, either to generate rental income or to preserve capital.

He added that many private investors remain unfamiliar with alternative investment products, while Cyprus’ relatively small domestic stock market further reinforces the appeal of property ownership.

Housing affordability is becoming a growing concern

Although Clerides dismissed suggestions of a housing bubble, he warned that rising property prices are already creating significant social consequences.

Lower-income households are finding it increasingly difficult to buy or even rent homes in several parts of the country.

Looking ahead, he suggested Cyprus may eventually need to rethink its urban planning policies, placing greater emphasis on higher-density development and apartment living, particularly within major cities.

Credit-fuelled bubble not supported by the data

Kapnisis believes the first-half figures indicate that 2026 is likely to match or slightly outperform the levels recorded in 2025.

According to KPMG’s analysis, Cyprus recorded approximately 26,000 property transactions worth a combined €6.5 billion during 2025.

While residential property prices have been rising faster than wages, Kapnisis said the market lacks the defining characteristic of a credit-driven housing bubble — excessive bank lending.

During the first five months of 2026, new residential mortgages totalled €605 million, compared with approximately €1.34 billion during the whole of 2025.

Based on residential property accounting for around 70% of total transaction values, he estimates that only 35% to 40% of new home purchases are financed through bank borrowing.

The remainder is funded largely through buyers’ own capital and overseas purchasers, who account for roughly 40% of the overall market.

While this reduces systemic financial risk, it does not eliminate it entirely.

Construction activity is increasing, but context matters

Kapnisis also cautioned against interpreting the 40% rise in licensed construction floor area as evidence of runaway development.

Part of the increase reflects statistical distortions following the restructuring of Cyprus’ District Administrations and the Department of Town Planning during the second half of 2024.

Administrative delays depressed permit approvals during early 2025, making year-on-year comparisons appear stronger in 2026.

Even so, he acknowledged that construction activity is genuinely expanding.

Overall, he believes the market remains underpinned by strong economic sectors including tourism, professional services and the relocation of international companies together with highly paid foreign employees, rather than speculative investment.

Key risks remain under close watch

Despite the positive outlook, Kapnisis identified several risks that require careful monitoring.

These include:

  • Housing affordability for domestic buyers.
  • Persistently rising construction costs.
  • Concentrated price growth in coastal and luxury markets.
  • Potential changes in interest rates.
  • Continued reliance on overseas buyers, whose purchasing decisions are influenced by global economic conditions.

Should overheating emerge, he expects it to appear first within these specific market segments rather than across the entire property sector.

Structural overheating rather than a property bubble

Agisilaou described the current environment as one of structural overheating, rather than a speculative bubble.

He said the 15% increase in property sales during the first half of 2026 clearly demonstrates strong demand and elevated market activity, but does not, on its own, prove that a bubble is forming.

Demand continues to be supported by permanent population growth, positive net migration, corporate relocations and lower interest rates, while housing supply remains relatively slow to respond.

Foreign demand is placing particularly strong upward pressure on both sale prices and rents in certain locations.

Meanwhile, although the increase in licensed construction projects indicates that developers are responding to market signals, it does not necessarily translate into an immediate increase in housing supply.

New developments require considerable time before they are completed and become available to buyers.

Housing affordability remains the biggest long-term challenge

According to Agisilaou, the greatest threat facing the Cyprus property market is not a sudden collapse in prices but the gradual erosion of housing affordability.

If house prices and rents continue to outpace income growth, he warned that the market risks becoming increasingly divided.

A growing number of local households could be forced to relocate to more affordable areas or settle for smaller and older properties, while premium locations continue to be driven by stronger international demand.


Cyprus construction costs & apartment prices continue to rise

Cyprus’ construction costs and property prices continue to climb, driven by higher material costs, strong demand and sustained building activity, according to new market analysis by Ask Wire.

Speaking about the latest market trends, Ask Wire CEO Pavlos Loizou said international steel and copper prices, rising energy costs, supply chain pressures and continued construction activity remain the main drivers behind higher building material costs.

Apartment prices rise sharply

Figures from the Central Bank of Cyprus show that apartment prices increased by 10.8% year-on-year during the first quarter of 2026, while house prices rose by 3%.

Ask Wire’s transaction data for the first half of 2026 also highlights significant regional differences in average apartment sale prices:

Limassol – ~€363,000

Paphos – ~ €262,000

Nicosia – ~€183,000

Larnaca ~ €171,000

Famagusta ~ €150,000

Loizou said Limassol remains Cyprus’ most expensive apartment market, largely due to its high-end beachfront developments and luxury residential towers.

“Paphos follows, ahead of Nicosia, Larnaca and Famagusta,” he said.

He added that although Nicosia’s market is primarily supported by domestic buyers, apartment prices have continued to rise compared with 2025.

“A typical two-bedroom apartment measuring around 75 to 90 square metres is generally priced close to, or slightly above, the average for each district. Final values depend on location, age, energy efficiency and, in coastal districts, proximity to the sea.”

Larnaca leads price growth

According to Loizou, Larnaca is recording the strongest annual increase in apartment prices, with values rising by approximately 8.9%, while price growth has begun to moderate in both Limassol and Paphos.

“Our data confirms this momentum,” he said.

“During the first half of 2026 we recorded 1,521 apartment transactions in Larnaca, the highest volume anywhere on the island.”

He attributed the city’s strong performance to several factors:

  • robust overseas demand;
  • greater affordability compared with Limassol;
  • a lower starting price base;
  • continued infrastructure improvements; and
  • stable rental yields from modern, energy-efficient one and two-bedroom apartments close to the coast.

Demand remains strong

Loizou said demand across the Cyprus property market remains robust with no signs of slowing.

“Property transactions reached a 17-year high in 2025, with transfers worth €4.7 billion. That momentum has continued into 2026.”

He noted that sale contracts increased by 13.8% during the first quarter of 2026, while Ask Wire’s own figures show strong transaction volumes across every district.

Foreign buyers continue to drive the market, accounting for as much as 75% of transactions in Paphos, supported by improving domestic demand as housing lending increased by 24.5% and mortgage interest rates fell to around 3.15%.

Loizou said the strongest demand continues to be for modern one and two-bedroom apartments near the sea, particularly those with high energy efficiency ratings.

Outlook for 2026

Looking ahead, Loizou expects property prices to continue rising during 2026, although at a more moderate pace.

He forecasts annual price growth of around 3% to 5% across Cyprus, with Larnaca expected to outperform the national average.

Newer apartments with strong energy performance are likely to achieve price growth of between 4% and 6%, he said.

While lower interest rates continue to support demand, affordability pressures, constrained housing supply and geopolitical uncertainty are expected to prevent another sharp surge in prices.

Large luxury homes may underperform as they rely more heavily on cautious high-net-worth buyers.

Overall, Loizou expects the market to remain resilient, with steady growth and no indication of a widespread price correction.