Cyprus property sales rise again as overseas demand grows

As reported earlier, Cyprus property sales continued to strengthen in July 2026, extending the steady growth seen across the island’s real estate market over the past year.

While Cypriot buyers remained the largest group of purchasers, overseas demand continued to make a significant contribution, particularly in the popular coastal areas.

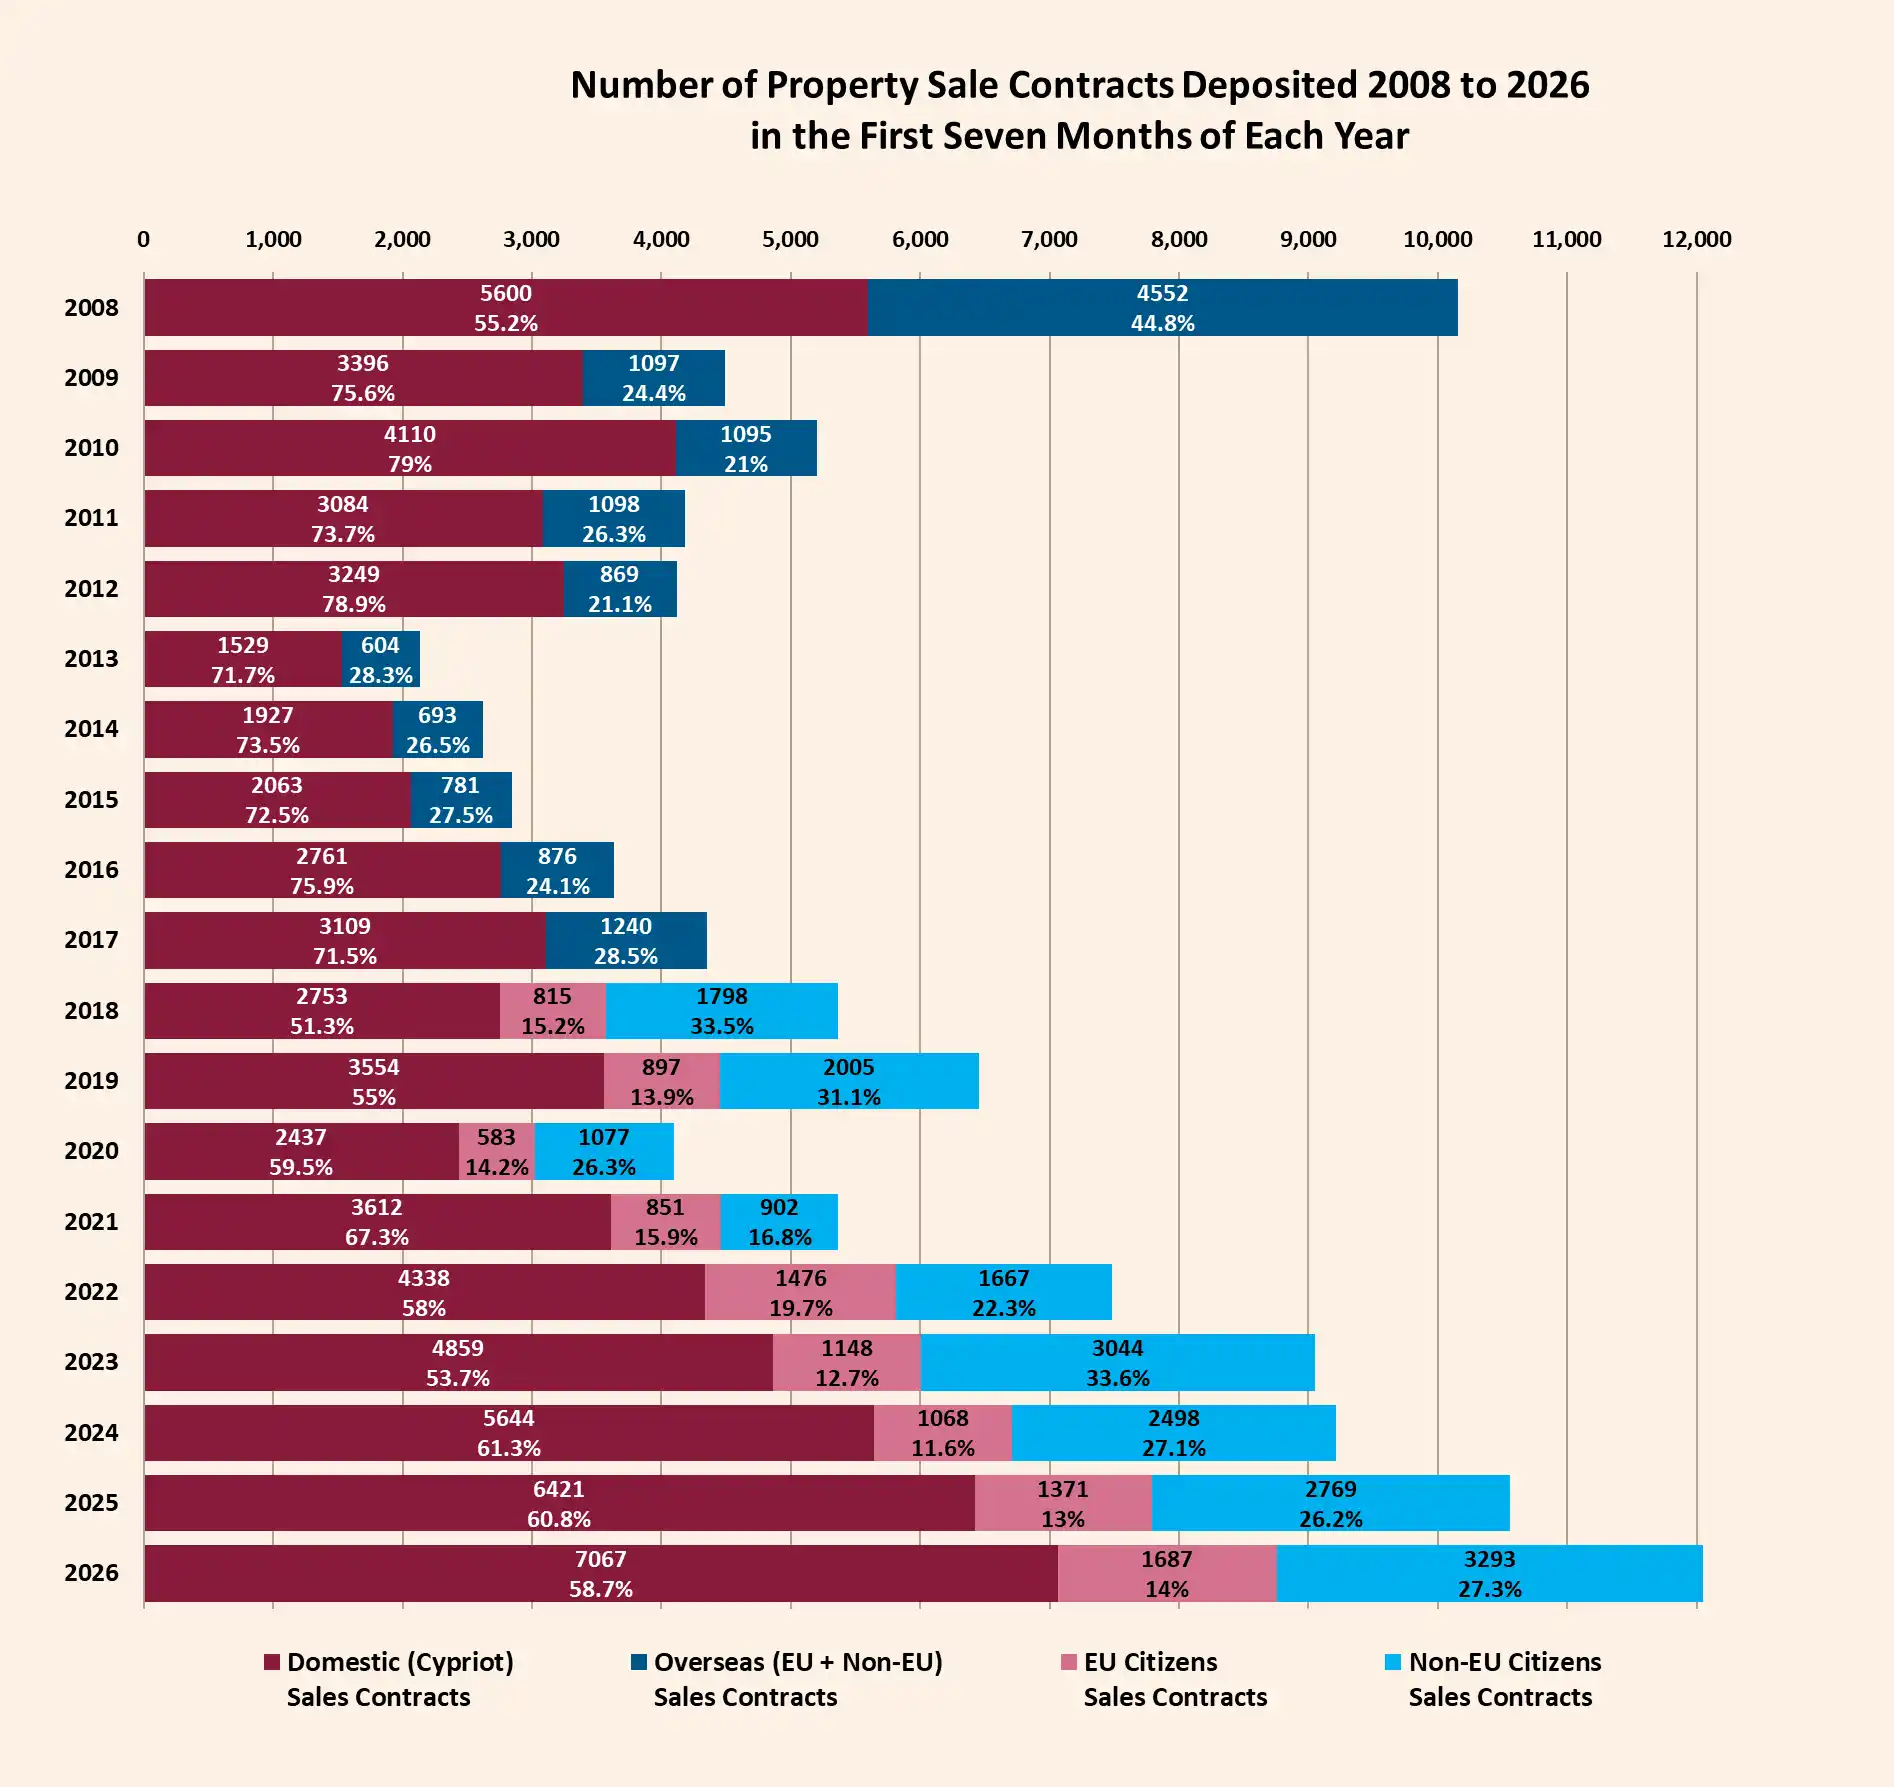
The chart below shows the year-to-date performance of each market segment dating back to 2008. It is worth noting that the Department of Lands and Surveys only began reporting separate figures for EU and non-EU buyers in 2018. Before then, all foreign purchases were grouped together under the category of overseas sales contracts.
Cyprus property sales market analysis July 2026

Domestic buyers remain the largest part of the market

Cypriot buyers accounted for 1,211 property sales in July, representing 59% of all transactions completed during the month. This compares with 1,080 sales in July 2025, an increase of 12%.

Performance varied across the districts.

Domestic sales declined in Larnaca, where transactions fell 13% to 232, and in Famagusta, where sales dropped 9% to 49.

However, stronger activity elsewhere more than made up for these falls. Limassol recorded the biggest increase, with sales rising 39% to 445. Paphos saw sales climb 29% to 129, while Nicosia recorded a more modest 4% increase to 358.

Domestic (Cypriot) contracts of sale deposited – 2025/2026 Comparison (July)


During the first seven months of 2026, every district recorded higher domestic sales than during the same period last year. Limassol led the market with growth of 24%, followed by Famagusta at 10%, while Paphos and Nicosia reported increases of 3% and 5% respectively.

Domestic (Cypriot) contracts of sale deposited – 2025/2026 Comparison

EU buyer activity records marginal growth

Property purchases by European Union citizens edged higher in July.

A total of 277 sales contracts were deposited by EU buyers, compared with 274 in July 2025, representing annual growth of just 1%.

Sales fell in Famagusta (35%), Limassol (32%) and Nicosia (20%). However, these declines were offset by strong increases in Larnaca, where sales rose 91%, and in Paphos, where they increased by 16%.

Contracts deposited by EU Nationals – 2025/2026 Comparison (July)


Year-to-date figures show that demand from EU buyers continues to improve.

Paphos remains the strongest-performing district, with sales increasing 46% compared with the first seven months of 2025. Larnaca followed with growth of 36%, while Nicosia and Limassol recorded increases of 10% and 2% respectively. Famagusta was the only district to record a decline, with sales down 3%.

Contracts deposited by EU Nationals – 2025/2026 Comparison

Non-EU buyers continue to drive market growth

Demand from non-EU buyers remained particularly strong during July.

A total of 552 property sales contracts were deposited by non-EU purchasers, compared with 478 in July 2025, representing annual growth of 15%.

Although sales in Nicosia fell by 16%, the remaining districts all recorded increases.

Larnaca posted the strongest growth, with sales rising 42% to 150. Famagusta followed with a 35% increase to 31 sales, while Limassol recorded growth of 10% to 190. Paphos also continued to perform well, with sales increasing 6% to 155.

Contracts deposited by non-EU Nationals – 2025/2026 Comparison (July)


The year-to-date figures underline the strength of overseas demand.

Sales to non-EU buyers have increased by 19% during the first seven months of 2026 compared with the same period last year. Every district recorded double-digit growth over the period.

Contracts deposited by non-EU Nationals – 2025/2026 Comparison

Overseas buyers continue to support Cyprus property sales

The latest figures confirm the continued appeal of Cyprus among international buyers.

Combined purchases by EU and non-EU citizens accounted for 41% of all property sales completed during the first seven months of 2026. Demand remains particularly strong in Paphos, reinforcing its position as one of the island’s most popular destinations for overseas purchasers.

Market Segment Summary Analysis 2026 Year to Date

Outlook

The July figures highlight a Cyprus property market that continues to show resilience.

Steady domestic demand, together with sustained interest from overseas buyers, is supporting sales across the island. Coastal districts, particularly Paphos, Limassol and Larnaca, continue to attract strong levels of international interest, helping to maintain the market’s positive momentum as 2026 progresses.
Cyprus property market surges 14% in first seven months of 2026

The Cyprus property market maintained its strong momentum during the first seven months of 2026, with property transactions rising by double digits both year-on-year and in July, according to the latest figures from the Department of Lands and Surveys.

A total of 12,047 contracts of sale were lodged with district Land Registry offices between January and July 2026, compared with 10,561 during the same period in 2025. This represents an annual increase of 14%, underlining continued demand across the island’s residential and commercial property sectors.

July also delivered another positive performance, with nationwide property sales increasing by 11% compared with the same month last year.

All districts report higher transaction volumes

The data show that every district recorded more property transactions during the first seven months of 2026 than in the corresponding period of 2025, highlighting broad-based strength across the Cyprus property market.

Limassol retains top spot

Limassol remained Cyprus’ busiest property market, recording 3,959 contracts of sale during the first seven months of 2026, up from 3,304 a year earlier. The district posted an impressive 20% annual increase, reinforcing its position as the country’s leading property hotspot.

Nicosia recorded 2,564 contracts of sale, compared with 2,432 during the same period in 2025, representing a more modest but still positive 5% increase.

Larnaca continued its steady upward trajectory, with transactions rising to 2,599 contracts of sale, compared with 2,343 in 2025. This equates to annual growth of 11%.

Paphos also enjoyed a particularly strong performance. Property sales climbed to 2,387, up from 1,995 in the first seven months of last year, marking a 20% increase.

Meanwhile, Famagusta recorded 538 contracts of sale, compared with 487 during the corresponding period of 2025, reflecting annual growth of 10%.

Total contracts of sale deposited – 2025/2026 Year-to-Date Comparison

July sales up 11.4%

During July 2026, a total of 2,040 contracts of sale were submitted to district Land Registry offices, compared with 1,832 in July 2025, representing a nationwide annual increase of 11%.

Limassol once again delivered the strongest performance, with transactions rising by 20% to 695 contracts of sale, up from 579 in July last year.

Paphos followed with a 15% increase, recording 395 transactions compared with 342 a year earlier.

Larnaca also reported healthy growth, with sales rising by 10%, from 395 to 436 contracts of sale.

Nicosia’s market remained broadly stable, with 423 transactions recorded compared with 422 in July 2025.

Famagusta was the only district to record a slight decline, with property sales slipping 3% to 91 contracts of sale, down from 94 during the same month last year.

Total contracts of sale deposited – 2025/2026 Comparison (July)

Outlook

The latest figures suggest that the Cyprus property market continues to demonstrate resilience despite broader economic uncertainties. With all districts reporting higher transaction volumes over the first seven months of the year and Limassol continuing to outperform, the market remains on course for another strong year if current trends persist.

Cyprus extends ‘Mortgage to Rent’ scheme until 30 September

Borrowers seeking to join Cyprus’ Mortgage to Rent Scheme have been granted an additional two months to submit their applications, after the Ministry of Finance announced an extension in response to strong public interest.

The application deadline, which had been due to expire on 31 July 2026, has now been extended until Wednesday, 30 September 2026, giving eligible homeowners more time to apply for the government-backed housing support programme.

Extension follows increased demand

In a statement issued today, the Ministry of Finance confirmed that the extension was approved due to the growing number of applications received in recent weeks.

The scheme reopened in May 2026, allowing eligible borrowers another opportunity to participate. While applications resumed earlier this year, the eligibility criteria and participation conditions remain unchanged.

The decision to extend the deadline suggests demand for the programme has accelerated as the original closing date approached.

(According to KEDIPES, a total of 4,269 applications were submitted between 2023 and 31 July 2026, including 929 received between 4 May and 31 July 2026. Of these, 1,211 applications have been approved, with 846 properties already transferred to KEDIPES.)

Applications must be submitted in person

Although application forms are available online as well as from regional offices, the Ministry has reminded applicants that completed applications must be submitted in hard copy only at one of the regional offices of the Cyprus Asset Management Company (KEDIPES).

Applications can be lodged at KEDIPES offices in:

  • 7 Grigori Afxentiou Street, Nicosia 1096
  • 97 Gladstonos Street, Oasis Complex, Block E, 3rd Floor, Limassol 3032
  • 5 Giorgou Christodoulidi Street, Larnaca 6041
  • 7 Kinyras Street, Corner of Koroivou Street, Galaxias Building, Shop 4, Paphos 8011
  • 4 Griva Digeni Street, 1st Floor, Paralimni 5281

Applicants should ensure all required documentation is included before submitting their forms.

Further information

Anyone seeking further information or guidance on the Mortgage to Rent Scheme can contact the KEDIPES customer service centre on +357 22 743400.

The latest extension provides eligible borrowers with a further opportunity to benefit from the scheme before the revised 30 September 2026 deadline.

Cyprus valuers warn against relying on online property valuations

The Cyprus Association of Property Valuation Professionals (SEEAK) has urged homeowners, buyers and investors to exercise caution when using online property valuation tools, stressing that automated estimates are only indicative and should never replace a comprehensive professional valuation.

In a statement, the association, a member of the Cyprus Chamber of Commerce and Industry (CCCI), said online platforms and automated valuation systems can serve as useful supporting tools by providing an initial estimate of a property’s likely value. However, they should not be regarded as definitive assessments.

Automated models cannot reflect every property

According to SEEAK, most online valuation platforms rely on automated models, publicly available datasets and standardised assumptions. As a result, they often fail to capture the unique characteristics, condition and individual features that influence the true market value of a property.

The association warned that automated estimates should be viewed as a starting point rather than an accurate reflection of a property’s worth.

Professional inspection remains essential

SEEAK said a reliable, evidence-based property valuation must be carried out by a suitably qualified professional valuer.

A thorough on-site inspection, assessment of the property’s physical condition, detailed understanding of the local market and application of recognised professional standards all form essential parts of the valuation process.

The association also warned that automated valuation results should not be relied upon when making significant financial, investment or lending decisions.

To illustrate the point, SEEAK compared online property valuations to searching medical symptoms on the internet. Just as an online diagnosis cannot replace a consultation with a doctor, an automated valuation cannot substitute for the professional judgement of an experienced valuer who has personally inspected the property.

International standards draw a clear distinction

SEEAK said its position is fully aligned with both international and European valuation standards, which clearly distinguish automated valuation models (AVMs) from professional property valuations.

The International Valuation Standards Council (IVSC) states that a fully automated model operating without the involvement of a qualified valuer cannot produce a valuation that complies with the International Valuation Standards (IVS). This is because such models do not apply professional judgement and therefore cannot provide an expert opinion on market value.

The latest IVS 2025, which came into force on 31 January 2025, introduces enhanced governance, data quality, modelling and quality assurance requirements. It also defines automated valuation models as systems that generate calculations without applying professional judgement.

In its position paper on the growing use of artificial intelligence in property valuations, the IVSC further emphasises that professional valuers must remain responsible for selecting data, evaluating valuation models and verifying the accuracy of results.

RICS and European banking rules support the same approach

SEEAK noted that the Royal Institution of Chartered Surveyors (RICS) adopts a similar position through its globally recognised Red Book valuation standards.

Where artificial intelligence, automated valuation models or valuation software are used, the resulting assessment can only be considered a formal written valuation if it has been reviewed and endorsed through the professional judgement of a qualified valuer.

The 2025 edition of the Red Book strengthens mandatory standards relating to automated valuation models while introducing additional provisions covering automation and artificial intelligence.

The association also highlighted guidance issued by the European Banking Authority (EBA) on loan origination and monitoring. These guidelines require properties offered as loan security to be valued by a professional valuer. Even where advanced statistical models are used as supporting tools, responsibility for the final valuation remains with the qualified professional.

Similarly, the European Valuation Standards published by TEGoVA, together with the European AVM Alliance, classify statistical valuation methods separately from full professional valuations, recognising their role as supporting rather than substitute tools.

Property valuation is a regulated profession in Cyprus

SEEAK is encouraging members of the public to understand the capabilities and limitations of every online property valuation service before relying on the results.

Where an accurate and dependable assessment of a property’s value is required, the association recommends instructing a qualified professional valuer.

It also reminds consumers that property valuation is a legally regulated profession in Cyprus, with valuations carried out by registered members of the Cyprus Scientific and Technical Chamber (ETEK) who are authorised to practise in the relevant professional discipline.

Cyprus reopens debate on rent increase caps

The debate over introducing caps on rent increases has returned to the forefront of Cyprus’ political agenda, as the island’s housing crisis continues to rank among its most pressing social and economic challenges.

Rapidly rising housing costs, particularly across the country’s largest urban centres, have made affordable accommodation increasingly difficult to secure for young people, families and lower-income workers. As a result, calls for direct intervention in the rental market are gathering momentum.

Proposed legislation returns to Parliament

A private members’ bill tabled by ALMA – Citizens for Cyprus MPs Odysseas Michaelides and Michalis Paraskevas has reignited discussion in Parliament, prompting a wider debate over the most effective way to tackle the country’s housing affordability challenges.

The proposed legislation aims to strengthen protections for tenants against excessive rent increases without restricting landlords’ freedom to set the initial rent. It would also leave the existing Rent Control Law unchanged.

Among its key provisions are:

  • A statutory cap on rent increases.
  • Minimum time intervals between rent reviews.
  • Formal notification requirements for landlords.
  • Legal safeguards allowing tenants to challenge disputed increases through the courts.

Supporters argue that the measures would provide greater certainty for tenants while maintaining the overall framework of the private rental market.

Property owners warn rent caps could worsen supply shortages

However, opposition to the proposal has been equally vocal.

Kyprianos Theocharides, President of the Cyprus Property Owners Association, argues that rent caps fail to address the underlying cause of the housing crisis.

According to Theocharides, high rents are primarily the result of an insufficient supply of homes rather than excessive pricing by landlords. He warns that administrative limits on rental increases could discourage both property owners and investors, reducing the number of homes available to let and making it even harder for first-time renters to find accommodation.

International experience cited in the debate

Critics of rent controls point to examples from overseas to support their concerns.

Berlin’s controversial Mietendeckel (“rent cap”), introduced in 2020, capped existing rents based on June 2019 levels and ordered mandatory rent reductions for overpriced units.

According to opponents of similar measures in Cyprus, the policy coincided with a decline in rental supply as some landlords withdrew properties from the market or opted to sell instead. The legislation was struck down in April 2021 by Germany’s Federal Constitutional Court on constitutional grounds.

Stockholm is also referenced as an example of long-term rent regulation. While existing tenants have benefited from relatively stable rents, critics argue that the system has contributed to lengthy waiting lists for new tenants and encouraged the development of an informal market for tenancy contracts.

Meanwhile, research from Stanford University examining rent control in San Francisco found that while existing tenants benefited from greater housing stability, the policy also reduced the availability of rental homes for new entrants to the market.

Calls for structural housing reforms

Alongside the debate over rent caps, policymakers are advocating broader structural reforms designed to increase housing supply.

Dimitris Georgiades, Chairman of the Council for Economic Competitiveness, argues that rising rents stem less from landlords’ behaviour than from longstanding structural shortcomings that have limited residential development.

Supporters of this approach advocate:

  • Faster planning and development approvals.
  • Improved urban planning policies.
  • Greater investment in residential infrastructure.
  • Measures to encourage the construction of new homes.

Attention has also turned to short-term holiday lets. Rather than banning such properties, proponents argue that authorities should focus on enforcing existing planning regulations and land-use rules.

In addition, some policymakers contend that previous investment-linked citizenship schemes artificially increased housing demand, contributing to sustained price inflation across the property market.

Finding the right balance

The parliamentary debate now extends well beyond the question of whether rent increase caps should be introduced.

Instead, it raises broader questions about the future direction of Cyprus’ housing policy.

On one side lies the urgent need to protect tenants from escalating housing costs. On the other are concerns that greater market intervention could reduce investment, constrain housing supply and ultimately make affordability even more difficult to achieve.

The challenge for policymakers will be to strike a balance between improving access to affordable housing while preserving the long-term health, stability and sustainability of Cyprus’ residential property market.

Lower rents require more homes, not more property taxes

0

Every time rents rise, the political debate follows the same familiar script. Calls emerge for rent caps, higher taxes on vacant properties, tighter restrictions on Airbnb, and new penalties for landlords.

These proposals may generate positive headlines and create the impression that policymakers are taking decisive action, but they fail to address the underlying cause of the housing crisis.

Rents are not increasing because landlords have suddenly become more greedy. They are rising because the supply of homes has failed to keep pace with demand. In Cyprus, that shortage is not simply the result of market forces. It is largely the consequence of years of ineffective planning, excessive bureaucracy and delayed infrastructure delivery.

Housing supply is the real problem

The basic economics of the housing market remain unchanged. When demand exceeds supply, prices rise. The rental market is no exception.

For years, the Cypriot state has struggled to create the conditions needed for a healthy flow of new housing. Instead of enabling development, public administration often slows it down through outdated planning processes and unnecessary delays.

Increasing the number of available homes is the only sustainable way to improve affordability over the long term.

Planning reform must replace political short-termism

Planning policy should provide certainty for both residents and investors. Instead, zoning decisions are too often characterised by exceptions, political intervention and piecemeal amendments.

Residential zones should be determined using transparent, evidence-based planning with a long-term outlook measured in decades rather than electoral cycles. Predictable planning rules encourage investment, increase housing delivery and reduce opportunities for speculation by those with privileged access to planning decisions.

A stable planning framework benefits the entire property market while helping to expand housing supply.

Delayed planning permissions increase housing costs

The planning approval process remains one of the greatest barriers to residential development.

It is difficult to justify projects waiting years for the necessary approvals before construction can begin. Every month of delay increases financing costs, which are ultimately passed on to homebuyers and tenants.

Lengthy bureaucracy also discourages investment and slows the delivery of much-needed housing to the market, placing further pressure on rents.

Streamlining planning permissions is therefore not simply an administrative reform—it is an essential housing policy.

Infrastructure should follow residential zoning

Planning reform alone is not enough.

When land is designated for residential use, roads, pavements, drainage systems and other essential infrastructure should be delivered promptly. Without these basic services, land may remain technically residential while being practically impossible to develop for decades.

The costs should reasonably be shared by landowners who benefit from the increase in land value. Those unable to contribute immediately could repay the costs later, at a fair interest rate, when they sell or develop their property.

This approach would unlock significant areas of residential land that currently remain undeveloped despite existing planning designations.

Airbnb is not the root cause

Short-term holiday rentals are frequently presented as the principal driver of rising rents. The reality is more nuanced.

In genuinely tourist areas, short-term accommodation is a legitimate economic activity that supports the wider visitor economy. In predominantly residential neighbourhoods, however, existing planning rules should be enforced consistently.

The issue is not Airbnb itself. The real problem arises when the state fails to uphold the land-use policies it has established.

Avoid repeating past mistakes

Cyprus should also avoid returning to policies that artificially inflate housing demand.

The disgraced golden passport programme created a surge in property demand, pushed prices sharply higher and damaged the country’s international reputation. Housing policy should never depend on temporary or distorted sources of demand that inflate prices without improving long-term housing supply.

Reform the state, not the landlord

Targeting landlords may be politically popular, but it does little to solve the structural imbalance between supply and demand.

The more challenging task is reforming the institutions responsible for planning, licensing and infrastructure delivery. Yet these are precisely the reforms capable of increasing housing supply, improving affordability and creating a healthier property market.

Without meaningful structural change, policies such as rent controls, additional taxes and further market restrictions may offer political reassurance, but they will do little to help the households struggling to pay their rent each month.

If governments are serious about lowering rents, they must stop treating the symptoms and begin addressing the cause: an inadequate supply of homes created by a planning system that has failed to deliver.