Cyprus short-term rentals see occupancy & prices fall

The Cyprus short-term rentals market is experiencing a softer tourist season, with accommodation providers reporting declines in both occupancy levels and nightly rates as the sector also pushes for stronger action against illegal holiday lets.

According to the president of the Self-Service Tourist Accommodation Association (STEK), Constantinos Karakontis, demand has eased compared with last year’s exceptionally strong performance, although trading conditions remain better than those experienced in 2024.

Speaking to Alpha TV, Karakontis said the market had slowed noticeably.

“This year is certainly moving at a slower pace compared with last year,” he said, adding that occupancy levels are down by between 10 and 15 per cent, while average prices have fallen by a similar margin.

Occupancy and prices under pressure

The latest figures suggest Cyprus’ short-term rental sector is facing increasing competition amid a more cautious tourism market.

While the number of properties advertised on major booking platforms has remained broadly stable at between 12,000 and 15,000 in recent years, only around 8,500 currently hold an official licence issued by the Deputy Ministry of Tourism.

The gap between licensed and unlicensed accommodation remains one of the industry’s biggest concerns.

Calls for stronger enforcement of illegal holiday rentals

STEK is backing legislative changes that would link the government’s licensing register directly with online booking platforms such as Airbnb and Booking.com.

Under the proposed system, registration numbers could be verified in real time, allowing platforms to remove listings that do not hold a valid licence.

Karakontis said this would help eliminate illegal operators and improve confidence across the sector.

“When the registration number is not the real one, the platforms can at the same time delete the property from the platform,” he explained.

Industry representatives argue that stronger enforcement would create a fairer marketplace for compliant operators while improving consumer protection.

Building safety concerns highlighted

Karakontis also questioned communication between public authorities following the collapse of an apartment building in Germasogeia, where one apartment had reportedly been operating as short-term tourist accommodation.

Although the property had received the necessary tourism permit, he suggested information held by the local district authority regarding the building’s condition had not been shared with the Deputy Ministry of Tourism.

Rather than introducing additional administrative procedures, he said authorities should publish lists of buildings deemed unsuitable for tourist accommodation, enabling operators and visitors to identify potentially unsafe properties more easily.

Short-term rentals and the housing market

The rapid growth of short-term rentals has frequently been blamed for reducing housing availability and driving up residential rents across Cyprus.

However, Karakontis rejected those claims, arguing that much of the sector’s expansion has taken place in established tourist destinations, including Famagusta and Paphos, rather than in areas experiencing the greatest housing pressures.

He acknowledged that managing thousands of independently operated properties remains challenging but maintained that enforcement should focus on illegal accommodation rather than imposing further regulation on licensed operators.

Outlook for Cyprus’ holiday rental market

Despite weaker occupancy rates and lower average prices this season, industry representatives remain optimistic that demand will remain above 2024 levels.

For many operators, however, improving regulatory oversight and removing unlicensed listings from online booking platforms are now seen as essential steps towards creating a more sustainable and transparent short-term rental market in Cyprus.
Cyprus home energy efficiency tops EU average despite income gap

Almost three in 10 people in Cyprus were living in homes with improved energy performance in 2025, according to the latest figures from Eurostat. While the country has outperformed the European Union average, the data also reveal a significant gap between wealthier households and those facing financial hardship.

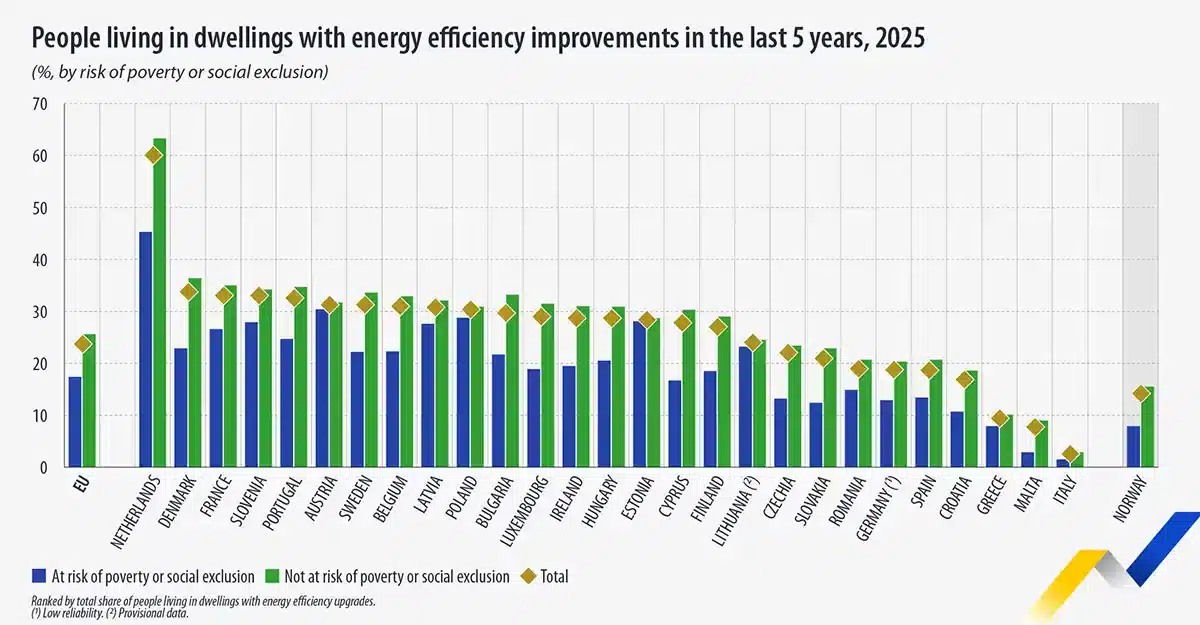
Eurostat found that 28% of Cyprus’ population lived in a property where energy efficiency improvements had been completed within the previous five years. This compares with the EU average of 23.9%, highlighting the growing uptake of energy-saving home upgrades across the island.

Cyprus home energy efficiency ranks above the EU average

Among EU member states, the Netherlands recorded the highest proportion of residents living in energy-efficient homes, at 60.5%. Denmark followed with 34%, while France and Slovenia each reported 33.3%.

By contrast, Italy recorded the lowest share at 2.6%, followed by Malta at 7.8% and Greece at 9.5%.

People living in dwellings with energy efficiency improvements in the last 5 years, 2025 (%, by risk of poverty or social exclusion)

The figures suggest that Cyprus has made steady progress in improving the energy performance of its residential housing stock, reflecting increased investment in home renovation and energy efficiency measures.

Financial divide remains a concern

Despite this progress, the data highlight a pronounced disparity between different income groups.

Among people considered at risk of poverty or social exclusion, just 16.7% lived in homes that had benefited from energy efficiency improvements during the previous five years. In comparison, 30.3% of those not considered at risk lived in upgraded properties.

As a result, Cyprus ranks among the EU countries with the widest gap between financially vulnerable households and those in a stronger economic position when it comes to accessing energy-efficient housing.

Across the European Union as a whole, 17.4% of people at risk of poverty or social exclusion reported living in homes with improved energy performance. That figure rises to 25.6% among households not considered at risk.

The findings underline both the progress Cyprus has made in improving residential energy efficiency and the continuing challenge of ensuring that lower-income households are not left behind as the country works towards its climate and housing objectives.

Cyprus rent cap proposal: New rules could limit rent increases

A new legislative proposal tabled in the House of Representatives seeks to introduce a legal framework aimed at protecting tenants of primary residences from excessive rent increases, while preserving landlords’ property rights and the principles of the free rental market.

The bill was submitted on behalf of ALMA – Citizens for Cyprus by MPs Odysseas Michaelides and Michalis Paraskevas.

Filling a gap in tenant protection

According to the explanatory memorandum accompanying the proposal, the legislation is designed to address a gap in protection for tenants living in properties that fall outside the scope of Cyprus’ Rent Control Law.

The proposed framework would apply exclusively to primary residence tenancy agreements. It would not introduce a new rent-controlled tenancy regime, grant tenants the right to remain in a property after the expiry of a lease, or interfere with the free negotiation of the initial rent between landlord and tenant.

Instead, the objective is to strike a balance between protecting tenants from excessive rent increases and safeguarding property rights while ensuring the smooth operation of the housing market.

Rent increases limited to once every two years

Under the proposal, landlords and tenants would remain free to agree on the initial rent at the start of a tenancy.

However, restrictions would apply to subsequent rent increases during the same tenancy or when renewing or extending an existing lease.

The bill proposes that rent may only be increased once every 24 months. Any increase would be limited to the lower of:

  • the percentage specified in the tenancy agreement; or
  • the percentage set by a decree of the Council of Ministers.

The legislation also establishes a statutory maximum increase of 6% every two years, unless the tenancy agreement provides for a lower increase.

New transparency requirements for landlords

Landlords would be required to provide tenants with at least 60 days’ written notice before any rent increase takes effect.

The notice would have to clearly state:

  • the current and revised rent;
  • the percentage increase;
  • the legal basis for the increase; and
  • the method used to calculate the permitted limit.

If these requirements are not met, the proposed increase would have no legal effect until the statutory obligations have been fulfilled.

Measures to prevent circumvention

The proposed legislation also contains safeguards designed to prevent landlords from bypassing the cap through additional charges or other financial obligations that effectively increase the overall rent.

Any contractual clause requiring a tenant to waive rights granted under the legislation would automatically be deemed void.

The proposal further introduces a rebuttable presumption of abusive conduct where a landlord refuses to renew or extend a tenancy and subsequently lets the same property to another tenant within six months at a rent exceeding the permitted increase.

In such cases, the landlord would be required to demonstrate that the decision was based on legitimate grounds, including:

  • occupying the property as their own residence;
  • selling the property;
  • carrying out substantial renovations; or
  • serious breaches of the tenancy agreement by the existing tenant.

Exception for major property improvements

The proposed cap could only be exceeded where landlords have undertaken substantial, documented improvements to the property.

Examples include:

  • energy efficiency upgrades;
  • significant electrical or plumbing works; and
  • extensive refurbishment projects.

Routine maintenance and repairs resulting from normal wear and tear would not qualify.

Any additional increase linked to improvement works could only be implemented after the works have been completed, the costs fully documented, and either:

  • the tenant provides written consent; or
  • the competent court grants approval.

District courts to handle rental disputes

The bill assigns exclusive jurisdiction for disputes arising under the proposed legislation to the relevant District Court.

The courts would have the authority to:

  • invalidate unlawful rent increases;
  • order landlords to refund overpaid rent; and
  • award compensation where attempts to circumvent the legislation are established.

The proposal also makes clear that the legislation would not apply retrospectively. It would affect only new tenancy agreements and lease renewals or extensions agreed after the law enters into force.

Balancing tenant protection and property rights

The proposed legislation aims to introduce targeted protections for tenants of primary residences that are currently outside Cyprus’ rent control framework.

According to the explanatory memorandum, the intention is not to replace the existing rent control system or create a new statutory tenancy regime. Instead, the proposal seeks to establish reasonable safeguards against excessive rent increases while maintaining an appropriate balance between tenant protection, landlords’ rights and the effective functioning of Cyprus’ housing market.

Download the draft bill and explanatory memorandum (Greek)

Where property taxes are highest and lowest in Europe

0

Buying a home in Europe? Taxes do not end when you collect the keys. From purchase to sale, property owners face a series of charges that can significantly affect the overall return on their investment.

Buying property in Europe means paying tax at almost every stage of ownership. Whether you purchase a holiday home, a buy-to-let investment or a permanent residence, taxes can apply when you buy, while you own, when you rent the property out and when you eventually sell.

The amount you pay varies enormously depending on the country. According to data from the Global Property Guide, which monitors real estate taxation in more than 80 countries, European property taxes remain among the most diverse in the world.

The four property taxes in Europe every buyer should know

Anyone purchasing property in Europe should understand four key taxes:

  • Transfer tax (or stamp duty), payable when purchasing a property.
  • Annual property tax, charged each year on a property’s assessed, cadastral or market value.
  • Rental income tax, payable on income generated from letting the property.
  • Capital gains tax, charged on any profit made when selling.

Comparing countries is far from straightforward. Tax rates are often published as ranges, valuation methods differ widely and many countries apply regional or municipal variations.

However, one country consistently appears among Europe’s most heavily taxed property markets.

Rental income tax: where landlords pay the most

For buy-to-let investors, rental income tax often has the greatest impact on profitability.

Global Property Guide estimates the tax payable by non-resident landlords earning monthly rental income of €1,500, €6,000 and €12,000.

At €1,500 per month, Denmark has Europe’s highest tax burden, with landlords paying 42.11% from the first euro earned. The Netherlands follows at 36%, while Finland levies 30%.

At the opposite end of the scale, Cyprus applies no rental income tax at this income level, while Luxembourg charges just 2.94%.

As rental income increases, the rankings change considerably.

At €12,000 per month, Belgium tops the list with a tax rate of 47.27%, narrowly ahead of Denmark at 43.22%. Germany and Greece both levy 41%.

Some countries maintain consistent tax rates regardless of rental income. Italy remains at 21%, Portugal at 28%, and the Netherlands at 36%, whether rental earnings are modest or substantial.

Countries with the steepest increases typically tax rental income alongside employment income.

Austria is a clear example. Rental income is taxed using the same progressive bands as salaries, beginning at 0% below €13,308 and rising to 55% on income exceeding €1 million. In practice, landlords are simply paying income tax on rental earnings.

Transfer tax: the cost of buying property

Purchase taxes can add tens of thousands of euros to the cost of acquiring a home.

Belgium once again sits near the top of the European rankings, with transfer tax reaching 12.5% of the purchase price in some regions. That is slightly above the UK’s highest Stamp Duty Land Tax rate of 12%, the Netherlands’ 10.4% and Luxembourg’s 10%.

Regional differences are significant.

A buyer purchasing a €500,000 property in Brussels or Wallonia without qualifying for relief could face a tax bill of €62,500.

However, owner-occupiers may benefit from generous reductions. Brussels exempts the first €200,000 of the purchase price for qualifying buyers, reducing tax on a €500,000 home to €37,500.

In Wallonia, eligible purchasers may qualify for a reduced 3% rate, cutting the tax bill to around €15,000. Buyers of qualifying social housing from public authorities pay no registration duty, while Flanders operates under a separate system of rates and reliefs.

At the other end of the market, Estonia and the Czech Republic charge no transfer tax.

Lithuania’s acquisition costs are among Europe’s lowest, amounting to around 0.4%, or approximately €2,000 on a €500,000 purchase.

Annual property tax: why headline rates can be misleading

Annual property taxes are often the most misunderstood part of European property ownership.

Countries use different methods to calculate taxable values. Some tax current market values, while others rely on cadastral or assessed values that may be decades old. The UK follows a completely different system based on council tax bands.

Spain illustrates why headline tax rates can be deceptive. Although property tax can reach 4.8% in certain municipalities, the rate applies to cadastral values rather than current market prices, meaning the actual amount paid is typically much lower.

For a property worth around €300,000, annual bills are generally far closer than headline percentages suggest.

In the UK, council tax typically ranges between €2,000 and €3,200 annually, depending on the local authority and valuation band.

France’s taxe foncière and Spain’s IBI usually fall between €700 and €1,800 because both are based on taxable values below market prices. Belgium’s précompte immobilier, calculated using a notional 1975 rental value, often produces similar annual bills.

Germany’s reformed Grundsteuer, introduced in 2025, is frequently lower than in many neighbouring countries, although bills now vary considerably between municipalities.

Cyprus and Malta stand apart by charging no annual property tax.

Capital gains tax: what happens when you sell

Selling a property can produce very different tax outcomes depending on where it is located.

Denmark imposes one of Europe’s highest capital gains tax burdens. Property gains are added to overall income and taxed at rates of up to 52.07%.

On a €250,000 profit, this could result in a tax bill of around €130,000, leaving the seller with approximately €120,000.

Malta adopts a very different approach. Rather than taxing the gain itself, it levies a 12% tax on the sale price as a transaction charge. This can fall to 5% for non-property traders selling within five years.

Germany rewards long-term ownership. Anyone who owns a property for more than ten years can generally sell free of capital gains tax. Selling before that period means any gain is taxed at the seller’s income tax rate, together with any applicable solidarity surcharge.

Which European country has the highest property taxes?

Looking across all four taxes, Belgium consistently ranks among Europe’s most heavily taxed property markets.

Transfer taxes remain among the highest in Europe, annual property taxes are well established and rental income tax can be particularly punitive. Only its relatively moderate capital gains tax, generally ranging between 16.5% and 33%, offers some relief.

At the opposite end of the spectrum sit Cyprus and Malta.

Cyprus applies no rental income tax at lower income levels and charges no annual property tax. Malta also has no annual property tax and uses a transaction-based system instead of conventional capital gains tax, making both countries among Europe’s most tax-efficient locations for property ownership.

The bottom line

For anyone buying property abroad, the purchase price tells only part of the story.

Transfer taxes, annual ownership costs, rental income tax and capital gains tax all influence the long-term profitability of an investment. The difference between owning an apartment in Brussels and a villa in Cyprus can amount to tens of thousands of euros over the lifetime of ownership.

For investors and second-home buyers alike, understanding property taxes in Europe is just as important as choosing the right location.

(Based on an article published in Euronews)

Cyprus Hotel Association calls for Airbnb limits and overnight levy

The Cyprus Hotel Association (STEK) has renewed calls for tighter regulation of Airbnb-style short-term rentals, urging the government to introduce annual letting limits, an overnight levy and tougher enforcement measures as part of a comprehensive overhaul of the current legislative framework.

The industry body said the findings of the recent report by Cyprus’ Audit Office reinforce longstanding concerns about both the content of the existing legislation and, more importantly, its inadequate implementation and oversight.

Illegal short-term rentals remain a concern

In a statement, STEK said it has repeatedly warned that the current framework contains significant weaknesses, allowing unlicensed holiday accommodation to continue operating and advertising without meaningful inspections or effective coordination between the relevant authorities.

According to the association, the continued presence of unlicensed properties demonstrates that the existing system is failing to fulfil its regulatory purpose.

STEK argued that maintaining a simple registration system is no longer sufficient. Instead, it is calling for a comprehensive regime of monitoring, inspections and enforcement to ensure that every operator in the hospitality sector complies with the same legal obligations and safety standards.

Housing market under pressure

The association warned that weak regulation extends beyond creating unfair competition for licensed hotels.

It argued that the rapid expansion of short-term rentals is placing additional pressure on Cyprus’ housing market, making affordable homes harder to find for permanent residents while creating disruption within local communities. The organisation also highlighted concerns over neighbourhood quality of life and visitor safety where accommodation operates outside the regulatory framework.

Proposed changes to Cyprus Airbnb regulations

STEK welcomed the Deputy Ministry of Tourism’s intention to review the legislation governing short-term rentals, describing the reform as an opportunity to address longstanding weaknesses while introducing measures already adopted across many European countries.

Among its recommendations, the association proposes:

  • More effective and systematic inspections to identify illegal accommodation providers.
  • Stronger enforcement powers supported by meaningful administrative and financial penalties.
  • Mandatory display of a property registration number on all online booking platforms.
  • Greater cooperation between digital platforms and the authorities to remove illegal listings quickly.
  • A maximum annual limit on the number of days a property can be let as short-term accommodation.
  • Powers for local authorities to restrict or prohibit short-term rentals in areas experiencing severe housing shortages, excessive nuisance or declining residential amenity.
  • A compulsory overnight levy for guests staying in short-term rental accommodation.
  • Uniform standards covering safety, health requirements and insurance across all accommodation providers.

Learning from European markets

STEK said experience elsewhere in Europe demonstrates that successful regulation of the short-term rental sector depends on clear rules, effective supervision and striking the right balance between tourism growth, housing affordability and the interests of local communities.

The association confirmed it will participate actively in the public consultation on the proposed legislation, submitting detailed recommendations aimed at creating a modern, enforceable regulatory framework.

It said the objective should be to establish a level playing field across the hospitality industry while protecting visitors, safeguarding local communities, supporting the residential housing market and strengthening the long-term sustainability of Cyprus’ tourism sector.

Audit Office uncovers widespread licensing concerns

The Audit Office previously reported that, as of 6 May 2026, there were 8,464 licensed self-catering accommodation properties registered in Cyprus’s official Register of Self-Catering Accommodation.

However, a sample review of online booking platforms found evidence that a significant number of self-catering properties are being advertised and operated without being registered or are displaying inaccurate licensing information. According to the Audit Office, this makes effective monitoring and regulatory oversight considerably more difficult. In many cases, properties could not be identified at all.

Of the 20 properties in the sample that investigators were able to identify, only six (30%) were properly registered and held a valid operating licence. Ten properties (50%) did not display a registration number and appeared not to be listed on the official register. In a further four cases (20%), although a registration number was provided, it did not match the official records. The number either related to an expired registration or belonged to a different property altogether.

In its response, the Deputy Ministry of Tourism acknowledged that a number of properties advertised on online booking platforms are either not registered with the Ministry or fail to display a registration number. It said the issue is expected to be addressed through the implementation of EU Regulation (EU) 2024/1028, adopted on 11 April 2024. While the regulation entered into force in May 2024, its key obligations became applicable from 20 May 2026.

Hotels also face licensing shortcomings

The Audit Office’s report also highlighted significant compliance issues across Cyprus’s hotel sector.

As of 27 April 2026, only 168 of the island’s 728 hotels and tourist accommodation establishments had secured a full operating licence under the relevant legislation, representing a compliance rate of just 23%.

A further 158 establishments, or around 22% of the total, were operating under temporary licences because they met certain qualifying conditions.

That leaves the majority of hotels and tourist accommodation providers (402 businesses, or 55% of the total) operating without a full licence or any form of temporary authorisation. According to the Audit Office, the figures demonstrate that the temporary measures and regulatory concessions introduced in recent years have failed to deliver the intended improvements in compliance.

The real cost of planning delays in the housing market

0

Planning delays are often blamed for increasing the cost of new homes. Yet the debate rarely moves beyond broad references to bureaucracy, with little discussion of the financial impact in real terms.

A simple, hypothetical, but entirely realistic, example illustrates the scale of the issue. Based on widely accepted assumptions used in property development appraisals, the figures below demonstrate how delays directly translate into higher housing costs.

Consider a medium-to-large residential development in Cyprus comprising 125 apartments.

  • Land acquisition: €7 million
  • Development and construction costs: €25 million
  • Total project cost: €32 million

Now compare two different scenarios.

In the first scenario, the developer acquires the site, secures all necessary planning approvals within six months and begins construction. The project is completed in two years.

In the second scenario, the same developer purchases the land but must wait four years before construction can begin because of delays in the planning approval process. The construction period remains unchanged at two years.

At first glance, the only difference appears to be time. In reality, the entire financial structure of the project changes.

The hidden cost of waiting

The first impact is the cost of holding the land.

A developer who commits €7 million to a site that cannot be developed for four years incurs a genuine financial cost. Assuming a relatively conservative cost of capital of 6%, the additional financing burden amounts to approximately €1.7 million.

There are also ongoing operating costs

Projects do not simply sit idle while approvals are pending. Developers continue to retain architects, engineers, planning consultants, legal advisers and administrative staff to manage, revise and progress applications. Even using a conservative estimate of €200,000 per year, four years of additional overheads add around €800,000 to the project.

Construction inflation creates a further layer of cost

Assuming annual construction cost inflation of 4% – without factoring in exceptional events such as geopolitical conflicts = the original €25 million construction budget rises by approximately €3.5–4 million over four years.

Before any return on investment is considered, the project has therefore incurred around €6.3 million in additional costs solely because of planning delays:

  • Land holding costs: €1.7 million
  • Construction inflation: €3.8 million
  • Administrative costs: €0.8 million

Total additional cost: approximately €6.3 million

Importantly, this example excludes potential increases in interest rates, energy prices, legal disputes, banking costs or changes to building regulations. If anything, it represents a conservative estimate.

The impact of planning delays on house prices

This is where the economic consequences become clear.

In the first scenario, the €32 million development requires total sales of around €38.4 million to achieve a 20% development margin. Across 125 apartments, the average selling price would be approximately €307,000 per home.

In the second scenario, total development costs increase to roughly €38.3 million solely because of the four-year planning delay. Maintaining exactly the same 20% profit margin, total sales must rise to around €46 million.

That equates to an average selling price of approximately €368,000 per apartment.

In other words, without the developer earning a single euro more, the average price of each home rises by around €60,000—almost 20%—purely as a result of planning delays.

Planning delays reduce housing supply

The consequences extend far beyond an individual project.

The longer it takes to complete one development, the fewer projects a developer can deliver over the course of a decade. Planning delays therefore increase not only the cost of each home but also reduce the overall supply of new housing.

That reduction in supply places even greater upward pressure on prices.

Ultimately, planning delays do not simply create additional costs for developers—they are passed on to homebuyers through higher sale prices. This is one of the most important points often overlooked in discussions about housing policy.

Any meaningful debate about affordable housing must therefore recognise the role of the planning system. When approvals take years rather than months, capital remains tied up, investment costs rise, housing delivery slows and the final bill is borne by those trying to buy a home.

Lengthy planning processes also make housing supply highly inelastic. When the market cannot respond quickly to rising demand, even modest increases in demand can result in disproportionately higher house prices.

Planning efficiency is therefore far more than an administrative issue. It is one of the key drivers of housing affordability.

Faster planning benefits the entire economy

Accelerating planning approvals does not mean weakening oversight or compromising environmental standards.

It means creating faster, more predictable and more efficient processes. Responsible developers are not asking for fewer checks; they are asking for existing checks to be completed within reasonable and predictable timescales.

The debate should therefore move beyond whether planning delays exist and instead focus on the measurable economic cost they impose.

Ultimately, this is not simply a question for property developers. It is about whether young people can afford to buy their first home, whether families can access reasonably priced housing and whether Cyprus can continue attracting high-quality investment that supports long-term economic and social prosperity.

Faster planning approvals are not merely a pro-development reform. They are a reform that benefits society as a whole.

(Translated from an article by Yiannis Misirlis, President of the Cyprus Property Developers Association)