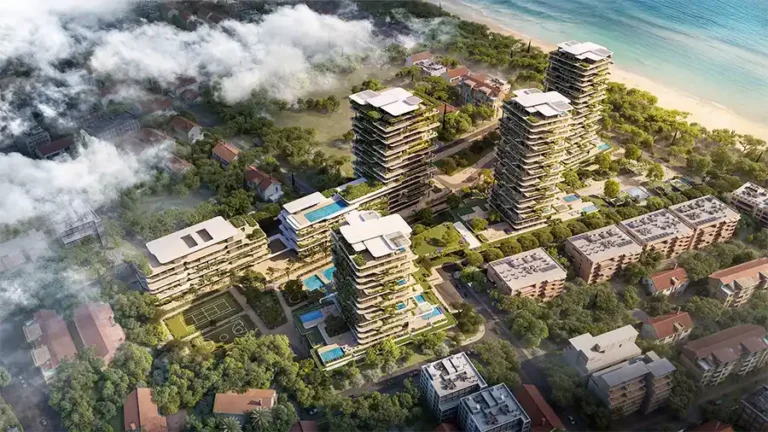
Two new high-rise projects worth €260m for Limassol

Limassol is set to welcome two landmark high-rise developments following approval from the Environmental Authority, paving the way for projects worth a combined total of over €260 million.

KEAN Soft Drinks Ltd development in Amathounta

The former KEAN factory site in Amathounta, Limassol, will soon be transformed into a €189 million high-rise development. The historic factory will be demolished to make room for a modern complex featuring four residential towers and one office building.

Two residential towers – Two residential towers, located on the south-eastern and south-western edges of the site, will each include a ground floor plus 19 residential storeys, with heights of around 84 and 85 metres. These will also feature 23 swimming pools with a capacity of 500 m³. Commercial areas and leisure facilities will be housed on the ground floor, while underground and semi-underground levels will accommodate parking.

Office building – A 17-storey office tower, approximately 71 metres high, will be located on the eastern side of the site, with parking on multiple levels.

Additional residential buildings – Two more towers will rise in the north-western and north-eastern corners of the development. One will be 59 metres tall with 13 residential floors and 17 swimming pools, while the other will reach 40 metres with nine residential storeys.

Community centre – The project also includes a 10-metre-high community hub on the eastern side, featuring nine communal swimming pools with a total capacity of 985 m³.

SolidVes Ltd mixed-use development in Apostolos Andreas

Alongside KEAN’s project, another significant mixed-use development worth €80 million has been approved by the Environmental Authority in Limassol’s Apostolos Andreas. Covering a plot of 14,715 m², the scheme by SolidVes Ltd will combine residential, office, and retail space.

Residential tower – The 14-storey residential tower will include around 75 apartments ranging from one to three bedrooms, a roof garden, underground parking, and retail shops at ground level along Paphos Avenue.

Office tower – The 13-storey office building will also include two basement levels, a café floor, and a rooftop garden. Amenities such as a gym, restaurant, cafeteria, and meeting rooms will be available for tenants. Office layouts will be flexible to suit buyer requirements.

Parking and accessibility – In total, the project will provide 498 parking spaces, including 17 dedicated for persons with disabilities. Approximately 20% of parking will be at ground level, with the rest underground.

Environmental considerations – Shading from the towers will mostly affect internal parking areas and green spaces during morning hours. In the afternoon, shadows will extend towards Omonia Avenue, but the avenue’s width is expected to minimise any adverse impact on neighbouring properties.

A new skyline for Limassol

With both developments approved, Limassol is set to see its skyline further transformed by two further high-rise projects that bring together residential, commercial, and leisure uses. These investments not only mark a new chapter for the city’s urban landscape but also highlight growing investor confidence in Limassol as a hub for premium mixed-use developments.
Loopholes exposed in property sales to third-country nationals

A new report by the Cyprus Audit Office highlights serious gaps in the property acquisition framework for third-country nationals, exposing outdated systems, legal loopholes, and weak oversight. The findings raise strategic concerns for the Republic of Cyprus and call for urgent policy reform.

Legal gaps and loopholes

According to the law, third-country nationals are permitted to acquire immovable property only for purposes of residence, professional premises, or industrial development, subject to restrictions on the number and use of such properties.

However, a 2011 amendment – introduced to align with EU law – removed these restrictions for EU-based companies, including Cypriot companies, even when controlled by third-country interests. This development created a “loophole” that remains open.

Furthermore, a 2013 circular that gave an “investment” character to property purchases encouraged commercial exploitation. The Audit Office stressed that issuing such flexible circulars without changes in the law raises questions of legality.

Third-country figures underestimated

Based on 2024 data, 27.35% of all property sales involved third-country nationals. However, the Audit Office considers this percentage “misleading” and significantly underestimated, as it does not include companies owned by third-country nationals operating through EU or Cypriot structures.

Oversight weaknesses

The Audit Office also identified serious flaws in supervisory mechanisms:

  • No objective criteria exist for assessing the financial status of applicants.
  • There is no effective check on the origin of funds used.
  • The IT system “Third-country Nationals” has remained outdated since 1999, with upgrade efforts still pending.
  • No substantial monitoring of property use takes place after acquisition.

Strategic concerns

The report stresses that current restrictions are largely superficial, as they can easily be bypassed through EU-based companies. At the same time, there are no reliable figures on the real percentage of property owned by third-country nationals.

The Audit Office recommends the creation of a new policy framework with clear objectives, taking into account the economic, geopolitical, and strategic interests of the Republic of Cyprus. This requires a modernised legal framework fully aligned with EU law.

Most EU member states have already adopted restrictions on property acquisition by third-country nationals, citing reasons of public security, health, or strategic interests – restrictions that Cyprus has not yet implemented.

(Translated & summarised from an article in Simerini)

Cyprus parliament resumes debate on jointly-owned buildings bill

The Cyprus Parliament has restarted discussions on a new bill to regulate jointly-owned buildings such as apartment blocks and housing complexes. The aim is for the law to be voted on before the end of the current parliamentary session.

AKEL MP Aristos Damianou, who chairs the Parliamentary Committee on Internal Affairs, said that although a law has existed for many years, it was never properly applied. Key parts of the old law, like the creation of management committees, were simply not enforced.

A fresh 80-page proposal has now been put forward. Damianou admitted a lot of technical work has gone into the draft but warned that even the best-written laws are useless if they cannot be applied in practice.

The debate will continue next week. However, Damianou said the bill still has issues that need detailed discussion before it can pass.

DIPA MP Marinos Moushouttas reminded that the government first submitted the bill in 2023, but it was sent back for further talks with stakeholders. He explained that it now combines three different proposals, all focused on improving how management committees operate and clarifying their legal powers.

He noted that Cyprus has around 200,000 jointly-owned buildings – home to nearly half of the country’s population. Yet, problems like unpaid communal fees, disputes between neighbours, and poor building maintenance remain common.

The aim of the new law is to make sure everyone pays their fair share and meets their responsibilities. At the same time, another related bill on dangerous buildings will be debated, addressing safety concerns such as falling balconies.

Interior Minister Constantinos Ioannou welcomed the renewed debate. He stressed that fixing disputes in jointly-owned buildings has been a government priority since 2023.

According to the Minister, the new law will:

  • Set out clear rights and obligations for owners and tenants.
  • Create a compulsory Reserve (Sinking) Fund for unplanned/unscheduled repairs and maintenance.
  • Give management committees more power and responsibility.
  • Make insurance for buildings and individual units mandatory.

Ioannou added that unpaid communal fees and a lack of insurance have left many buildings unsafe, creating risks for both residents and the public. He thanked MPs and stakeholders for working together on the draft and said he hopes it will soon become law.

Cyprus CPS fines banks €1.4 million for unfair contract clauses

The Bank of Cyprus and Eurobank (formerly Hellenic Bank) must amend thousands of mortgage agreements after rulings by the Cyprus Consumer Protection Service (CCPS). The two banks were fined €1.4 million after more than 22,000 contracts were found to contain unfair terms.

For the Bank of Cyprus, the decision concerns 14,810 loans concluded since June 2021, mostly with consumers aged 20–45. The contested clauses involved the right of retention, account consolidation and set-off, customer notification obligations, and property revaluation costs.

The Bank has agreed to bring these terms into line with legislation, showing willingness to safeguard consumer rights. The CCPS noted improvements in wording and transparency in revised contracts and considered the Bank’s cooperation as a mitigating factor.

The Bank of Cyprus has been ordered to stop using the clauses within 60 days and avoid reinstating them in future agreements. It was fined €800,000, plus €1,000 for every day of continued use after the deadline.

In the case of Eurobank (formerly Hellenic Bank), 7,456 housing loans issued since August 2022 contained unfair terms on repayment methods, collateral, insurance, base interest rates, fees, reporting obligations, events of default, set-off, lien, and general conditions. The CCPS ruled these breached Articles 50 and 52 of the 2021 Consumer Protection Law, stressing that their repeated use in long-term contracts created financial strain for borrowers while benefiting the Bank. This was treated as an aggravating factor.

Mitigating factors included lack of fraud, no evidence of intent to exploit vulnerable groups, and the Bank’s cooperation. Eurobank also proposed amendments to comply with the law. As with Bank of Cyprus, the Service acknowledged improvements in clarity and transparency in revised terms.

Eurobank has been ordered to cease use of the clauses within 60 days, including in existing agreements. It was fined €600,000, plus €1,000 per day for any continued application.

According to the CCPS, both decisions aim to ensure compliance with consumer law, improve transparency in mortgage contracts, and strengthen protection for thousands of borrowers.

The Association for the Protection of Bank Borrowers (SYPRODAT) described the decision of the Consumer Protection Service to impose fines on the Bank of Cyprus (€800,000) and on Eurobank (€600,000) for abusive clauses in mortgage loan agreements as a “significant turning point”.

(Translated & summarised from a Greek article in StockWatch)

New bill to regulate jointly-owned buildings in Cyprus

As revealed earlier today by the Greek language Phileleftheros, the new bill to address the many problems of jointly-owned buildings does very little to address the single biggest headache for management committees – owners who simply refuse to pay their communal fees.

Under the new bill, nothing prevents an owner from ignoring their communal fee obligations for years, continuing to live in the property, even passing it on in their will – with no consequences until the property is sold.

In situations where the owner rents the property, their tenant can pay the communal fees to the management committee and take that amount off their rent they pay to the owner.

In cases where the owner doesn’t rent the property, the only option left to Management Committees remains the courts, a route so costly and slow that it offers no solution to the immediate need for the communal fees required to insure, maintain and manage the building.

What’s in the new jointly-owned buildings bill?

The proposed law, which has already undergone revisions, introduces a framework for the proper management, inspection, and maintenance of jointly-owned buildings. Interior Minister Konstantinos Ioannou has sent a formal letter to the committee, which will resume discussions on on the subject this Thursday.

One of the key provisions enables management committees to commission structural, mechanical, and electrical inspections by qualified professionals registered with the Cyprus Scientific and Technical Chamber (ETEK).

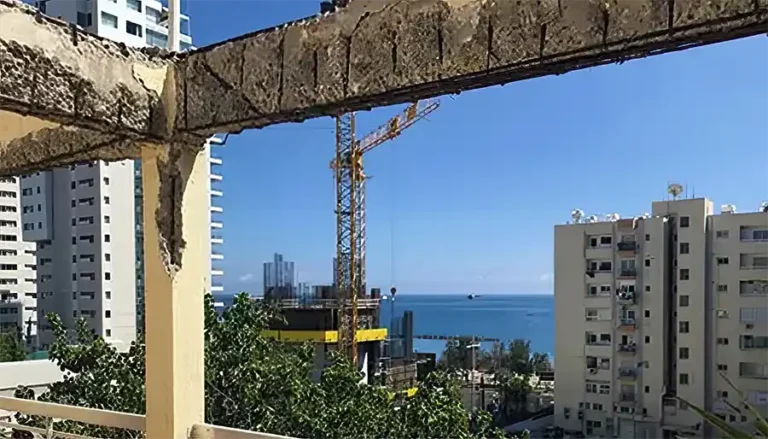
The absence of such inspections in the past has left many buildings – particularly older apartment blocks – vulnerable to neglect, with balconies collapsing and walls deteriorating (as shown in the photo above.) If approved, owners and residents will, for the first time, gain a clear picture of the structural soundness of their homes.

Jointly-owned buildings inspection & maintenance opportunity missed

A controversial amendment removed the requirement for regular mandatory inspections, which would have guaranteed consistent upkeep. Instead, inspections will now be at the discretion of each management committee and dependent on available funds. The minister, however, indicated that the provision might be reinstated in a future amendment of the existing Streets and Buildings Law.

Meanwhile, the bill requires management committees to set up a reserve (sinking) fund for unplanned repairs and maintenance work.

Financial obligations for owners

Under the new law, owners will contribute to:

  • Heating costs: covering fuel, maintenance, and repairs of central heating systems (where applicable).
  • Communal fees: including cleaning staff salaries, cleaning supplies, lift maintenance, electricity and water for shared areas, decoration, sewage emptying, and other related expenses.
  • Other expenses: insurance, general repairs, plumbing, electrical installations, insulation works, and environmental upgrades.

Tackling non-payment of communal fees

The most significant source of disputes in jointly-owned buildings is the non-payment of communal fees. The bill introduces a measure that prevents the sale of a property if the owner has not settled outstanding charges. Management committees will be authorised to issue certificates confirming payment, removing obstacles to property transfers – provided no other debts remain.

Legal review and technical improvements

The revised draft has passed legal review by the Attorney General, confirming no constitutional or legal barriers. Several technical enhancements have also been incorporated, including:

  • Clear definitions for GDPR compliance, management companies, and the register of owners.
  • Appointment of district self-governing authorities as responsible bodies.
  • Introduction of mediation procedures for disputes between owners and committees.
  • New provisions on fire safety systems and personal data protection.

Why this matters

As the Attorney General highlighted, the bill is crucial to address long-standing shortcomings in the management of jointly-owned buildings. Many properties have suffered from poor or non-existent maintenance, with serious safety risks for residents and the public.

But while the new bill appears to be a step in the right direction, it fails to address some of the problems with jointly-owned buildings; mandatory safety inspections & maintenance have been ruled out – and the most critical issue, non-payment of communal fees, has yet to be fully resolved.

The complexities of constructive trusts and third-party liability

0

Trusts are a fundamental component of equity law, designed to manage assets for the benefit of specific beneficiaries. Among the various types of trusts, constructive trusts are particularly complex and involve intricate legal principles, especially when it comes to third-party liability in cases of breach.

This article delves into the nuances of constructive trusts and explores the circumstances under which third parties may be held liable for losses incurred by beneficiaries due to a breach of trust.

Constructive trusts: an overview

Constructive trusts are not formed by a formal agreement but are imposed by law to prevent unjust enrichment or fraud. They are often created when someone wrongfully possesses property that should belong to someone else. This type of trust ensures that the person who has been wronged, receives the property or its equivalent value.

A key area of concern in the realm of constructive trusts is the liability of third parties—those who are neither trustees nor fiduciaries—when they assist in or benefit from a breach of trust. The complexity arises from determining the extent of their knowledge and the role they played in the misappropriation of trust assets.

Third-Party liability: dishonest assistance

One of the primary bases for holding a third party liable in cases of breach of trust is “dishonest assistance.” This doctrine applies to individuals who knowingly assist in a breach of trust, even if they never had possession or control of the trust property.

The landmark case Royal Brunei Airlines Sdn Bhd v Tan established the criteria for dishonest assistance. The court ruled that for a person to be held liable, three elements must be satisfied:

  1. Breach of Trust: There must be an initial breach of trust.
  2. Assistance in the Breach: The defendant must have assisted in this breach.
  3. Dishonesty: The defendant must have acted dishonestly.

Interestingly, the standard for dishonesty is objective. It is determined based on what a reasonable person would consider dishonest under the circumstances, rather than the defendant’s own perception of their actions. Subsequent cases, such as Twinsectra Ltd v Yardley and Dubai Aluminium v Salaam, have refined this test but maintained the emphasis on an objective standard.

The case of Paul: an example of dishonest assistance

Consider the example of Paul, a bank branch manager who allowed Robin, an agent managing finances for a principal, Oldbooks, to transfer funds from Oldbooks’ account into his own. Despite knowing about Robin’s financial troubles and previous misappropriations, Paul did not intervene or inquire further, allowing the transaction to proceed.

Applying the principles from Royal Brunei, Paul could be deemed a constructive trustee due to his dishonest assistance. He knew enough to be suspicious, but chose not to act, demonstrating a conscious disregard for the potential misuse of trust funds. Courts have held that such wilful blindness can satisfy the dishonesty requirement, thus making Paul liable for any losses suffered by the beneficiaries of the trust.

Knowing receipt: another avenue for liability

Apart from dishonest assistance, third parties can also be held liable under the doctrine of “knowing receipt.” This concept applies when someone receives trust property, knowing it was transferred in breach of trust.

For liability under knowing receipt to be established, three conditions must be met:

  1. Disposal of Assets in Breach of Trust: The property must be disposed of in a way that breaches a trust or fiduciary duty.
  2. Beneficial Receipt: The defendant must receive some benefit from the transferred property.
  3. Knowledge of the Breach: The defendant must know or have reasons to suspect that the property was transferred in breach of trust.

If we consider the case of the bank managed by Paul, it could also be held liable for knowing receipt. If Paul, as the branch manager, is considered the “directing mind” of the bank, his knowledge and actions can be attributed to the bank itself. Thus, if Paul knew or should have known about the misuse of the funds, the bank could also face liability for failing to act on this knowledge.

Corporate liability and the role of employees

The role of employees in corporate liability cases under trust law is another complex issue. As seen in Polly Peck International v Nadir (No 2) and MT Realisations Ltd v Digital Equipment Co Ltd, companies can be held liable for the actions of their employees if those employees are deemed to be the “directing mind” of the company.

In trust law, if an employee like Paul, acting within the scope of his employment, assists in a breach of trust or fails to act on suspicious transactions, the company may be held accountable for these actions under the principle of vicarious liability.

Conclusion: The evolving landscape of trusts law

Trust law, particularly concerning constructive trusts and third-party liability, is a continually evolving field. Courts strive to balance the principles of fairness and justice, ensuring that beneficiaries are protected from losses due to breaches of trust while also recognizing the limits of liability for third parties who may not fully understand the implications of their actions.

As the cases discussed illustrate, the application of doctrines such as dishonest assistance and knowing receipt requires careful analysis of the facts and the extent of each party’s knowledge and actions. The law imposes a duty of honesty and reasonable conduct on all individuals and entities dealing with trust property, reinforcing the importance of acting with integrity in all fiduciary relationships.

Ioannis A. Pitsillos LLB, MBA
Partner at Polycarpos Philippou & Associates LLC