Cyprus building activity soars in first two months of 2026

Building activity across Cyprus recorded strong growth during the first two months of 2026, according to the latest figures from the Statistical Service, highlighting continued momentum in the residential property sector.

The total floor area of licensed developments increased by 54.9% year-on-year, while project values, building permits and the number of planned residential units also posted substantial gains.

Between January and February 2026, the total floor area of licensed projects reached 661,400 square metres, compared with 427,100 square metres during the same period in 2025.

Residential building development leads construction growth

The sharp increase was primarily driven by residential developments, where licensed floor area rose by 79.7% to 578,609 square metres, up from 321,930 square metres a year earlier.

Civil engineering projects also recorded exceptional growth. Licensed floor area surged by 1,749.7%, reaching 16,666 square metres compared with just 901 square metres during the corresponding period of 2025.

In contrast, non-residential buildings experienced a decline, with licensed floor area falling by 36.6% to 66,108 square metres.

Larnaca records the strongest regional growth

At district level, Larnaca posted the largest percentage increase in licensed development area. Floor space rose to 174,400 square metres from 45,900 square metres a year earlier, representing growth of 279.7%. Compared with 2019, the increase stands at 342.7%.

Paphos followed with a 114.6% rise, reaching 79,500 square metres. Relative to 2019, licensed development area in the district has increased by 213.6%.

Nicosia recorded the highest overall volume of licensed development, reaching 217,400 square metres. This represented a 51.4% increase compared with the first two months of 2025 and a 214.9% rise compared with 2019.

Limassol reported 174,500 square metres of licensed development area, up 4.8% year-on-year and 18.9% higher than 2019 levels.

Famagusta was the only district to register a decline. Licensed floor area fell by 54.3% to 15,600 square metres from 34,100 square metres during the same period last year. Despite the annual drop, activity remained 263.4% higher than in 2019.

Overall, the total licensed development area across Cyprus increased by 54.9% compared with the first two months of 2025 and by 132.1% compared with 2019.

Project values and building permits continue to rise

The total value of licensed developments reached €825.1 million during January and February 2026, up 56.5% from €527.1 million in the corresponding period of 2025.

Residential projects accounted for much of the increase, with their value climbing by 78.6% to €649.7 million from €363.7 million a year earlier.

Civil engineering project values rose by 104.9% to €64.2 million. The value of permits for land subdivision increased by 102.4%, while road construction permits recorded a 229.0% rise.

Meanwhile, the value of non-residential developments declined by 21.0% to €100.2 million from €127.0 million.

A total of 1,500 building permits were issued during the first two months of 2026, compared with 1,008 permits during the same period in 2025, representing growth of 48.8%.
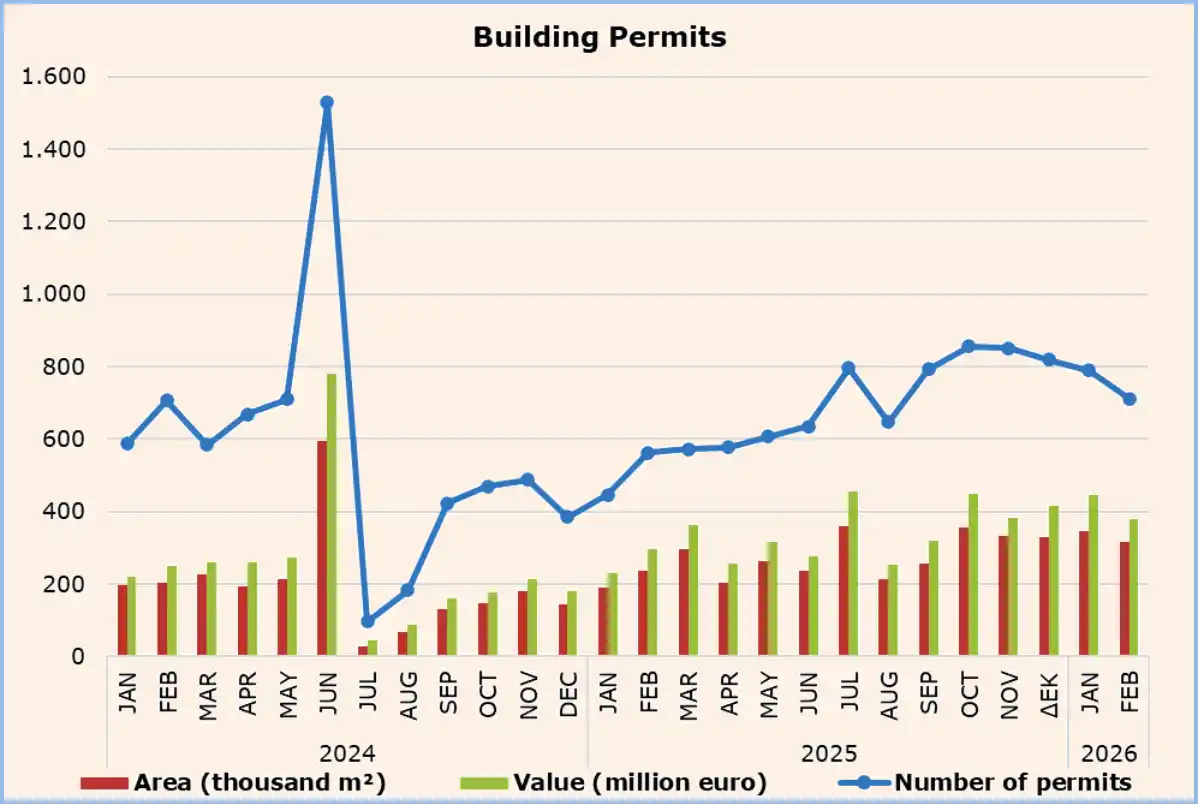
Cyprus Building Permits - February 2026

In February alone, authorities issued 711 building permits with a combined value of €379.9 million and a total floor area of 314,700 square metres.

Permits for residential buildings increased by 53.4%, while civil engineering permits rose by 40.6%. Land subdivision permits grew by 54.9%, and permits for road construction more than quadrupled, increasing by 328.6%. Non-residential building permits recorded a more modest rise of 7.9%.

Nearly 3,500 new homes planned

The permits issued during the first two months of 2026 are expected to result in the construction of 3,463 residential units, compared with 1,932 units during the same period last year, representing growth of 79.2%.

Detached houses increased by 40.2% to 610 units, while semi-detached homes rose by 6.6% to 227 units.

The strongest growth was recorded in apartment developments. Planned units in residential apartment buildings jumped by 115.0%, reaching 2,563 units compared with 1,192 a year earlier.

Mixed-use apartment developments moved in the opposite direction, falling by 31.5% to 63 units.

The latest figures underline the strength of Cyprus’ residential property market, with housing developments continuing to drive construction activity, investment and new supply across much of the island.
Cyprus property market analysis: May 2026 sales data

As reported yesterday, property sales in Cyprus continued their upward trend in May 2026, extending the steady growth seen across the real estate market over the past year.

According to the latest figures from the Department of Lands and Surveys, a total of 1,723 property sales contracts were deposited during May, representing a 5% increase compared with the same month last year.

While Cypriot buyers remained the largest group in the market, overseas purchasers continued to play a significant role, particularly in coastal districts where foreign demand remains a major driver of activity.

The chart below shows the year-to-date position of each market segment dating back to 2008. Note that it wasn’t until 2018 that the Department of Land & Surveys produced separate figure for EU and Non-EU buyers. Before 2018, all foreign purchases were recorded together as “Overseas Sales Contracts” combining both groups.

Cyprus property sale contracts January - May 2025

Domestic buyers remain the market’s largest segment

Cypriot purchasers accounted for 1,081 property sales in May, representing 62.7% of all transactions completed during the month. This compares with 1,055 sales in May 2025, an increase of 6%.

Performance varied considerably between districts. Domestic sales declined in Nicosia, where transactions fell 13% to 281, and in Famagusta, where sales dropped 37% to 29.

However, stronger activity elsewhere more than offset those declines. Paphos recorded the largest increase, with sales rising 34% to 147. Limassol and Larnaca also posted gains of 8%, reaching 368 and 256 sales respectively.

Domestic (Cypriot) contracts of sale deposited – 2025/2026 Comparison (May)

Looking at the first five months of 2026, all districts recorded higher domestic sales compared with the same period last year. Famagusta led the way with growth of 22%, followed by Limassol at 11%, Larnaca at 8%, while Paphos and Nicosia both reported increases of 4%.

Domestic (Cypriot) contracts of sale deposited – 2025/2026 Comparison

EU buyer activity surges, led by Paphos

Property purchases by European Union citizens recorded the strongest growth of any market segment during May.

EU buyers deposited 241 sales contracts, up 31% from the 184 recorded in May 2025.

Paphos remained the most popular destination for EU purchasers, with transactions soaring 83% to 88 sales. Famagusta also experienced strong growth, with sales increasing 82% to 20, while Larnaca recorded a 50% rise to 54 sales.

Nicosia saw a modest increase in activity, while Limassol was the only district to record a decline, with sales falling 18% to 56.

Contracts deposited by EU Nationals – 2025/2026 Comparison (May)

Year-to-date figures show continued momentum among EU buyers. Paphos leads the market with a 46% increase in sales compared with the first five months of 2025, followed by Larnaca at 31% and Nicosia at 19%. Limassol remained largely unchanged, while Famagusta recorded a 6% decline.

Contracts deposited by EU Nationals – 2025/2026 Comparison

Non-EU demand holds steady despite minor decline

Sales to non-EU buyers eased slightly during May, falling by just 1% year-on-year.

A total of 401 sales contracts were deposited by non-EU purchasers, compared with 405 during the same month in 2025.

The largest declines were recorded in Nicosia, where sales fell 27% to 19, and Limassol, where transactions slipped 6% to 109. Paphos also recorded a small decline of 3%, with 141 sales.

In contrast, Larnaca continued to attract growing overseas interest, posting a 13% increase to 110 sales. Famagusta also reported growth, with sales rising 10% to 22.

Contracts deposited by non-EU Nationals – 2025/2026 Comparison (May)

Despite the slight monthly decline, non-EU demand remains robust. Year-to-date figures show double-digit increases across all districts during the first five months of 2026, underlining the continued importance of international buyers to the Cyprus property market.

Contracts deposited by non-EU Nationals – 2025/2026 Comparison

Overseas buyers continue to shape key regional markets

Foreign buyers remain a dominant force in several areas of Cyprus, particularly in Paphos.

The district continues to attract significant interest from both EU and non-EU purchasers. During May, non-EU buyers purchased more properties than Cypriots, while combined sales to overseas buyers were more than double the number of transactions completed by domestic purchasers.

The latest figures reinforce the ongoing appeal of Cyprus among international investors and lifestyle buyers, with overseas demand continuing to provide a substantial contribution to overall market activity despite economic uncertainty in several global markets.

Market Segment Summary Analysis 2026 Year to Date

The May data highlights a market that remains resilient, supported by both domestic demand and sustained interest from foreign buyers, particularly in the island’s most popular coastal locations.

The Rocks: €mega development planned in Pentakomo, Limassol

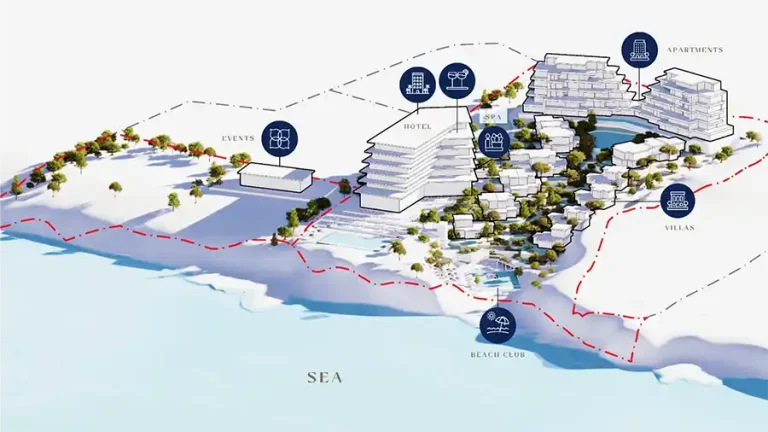
A major tourism and real estate development known as The Rocks has been proposed by DRL5COMOS PROPERTIES LTD in the community of Pentakomo, in the Limassol district.

The company has submitted an Environmental Impact Assessment (EIA) to the Environmental Authority, with the proposed development currently undergoing a public consultation process.

According to the project’s master plan, The Rocks will comprise a mixed-use tourism development, with operations expected to commence in 2029.

The scheme will include a 126-room hotel, 26 villas, 73 apartments and a beachfront service area covering 1,180 square metres.

Mixed-use resort development planned for 2029

The development has been designed as a large-scale coastal destination combining hospitality, residential accommodation and leisure facilities.

A total of 240 parking spaces are planned across the site, including:

  • 70 spaces for the hotel
  • 26 spaces for the villas
  • 94 spaces for the apartments
  • 50 spaces for the beachfront service area

Hotel and wellness facilities

The hotel will feature 126 rooms, a 900-square-metre spa and wellness centre, and six food and beverage outlets covering a combined area of 990 square metres.

The dining facilities will provide seating for 480 guests indoors and a further 300 guests outdoors.

The total floor area of the hotel will reach approximately 14,000 square metres.

Villas and apartments form key residential development

The residential component will consist of 26 villas with a combined floor area of 3,480 square metres.

In addition, 73 apartments are planned, covering a total area of 6,700 square metres. The apartment mix will include:

  • 50 one-bedroom apartments of 60 square metres each
  • 20 two-bedroom apartments of 85 square metres each
  • Two three-bedroom penthouses of 200 square metres each
  • One four-bedroom penthouse of 350 square metres

The apartment complex will also include communal facilities and a reception area spanning 700 square metres.

Beachfront facilities and public infrastructure

The beachfront service area will cover 1,050 square metres and will include:

  • A 700-square-metre indoor restaurant and bar
  • A 480-square-metre outdoor terrace
  • An outdoor swimming pool and sunbed area

The overall site extends across 34,714 square metres. As part of the development, 3,871 square metres will be allocated to public green space, while 2,456 square metres will be dedicated to road infrastructure. The remaining 28,387 square metres will form the main development plot.

The project also includes a dedicated access point linking the external road network with the internal roads and parking areas within the development.

Existing buildings currently located on the site will be demolished to make way for the new scheme.

Environmental review underway

The submission of the Environmental Impact Assessment marks a key stage in the planning process. The project is now subject to public consultation before any final approvals are granted.

If approved, The Rocks is expected to become one of the most significant tourism and residential developments proposed for the Limassol coastline in recent years, adding new hospitality capacity and high-end residential accommodation to the area.

Unsafe buildings alert amid Limassol development growth

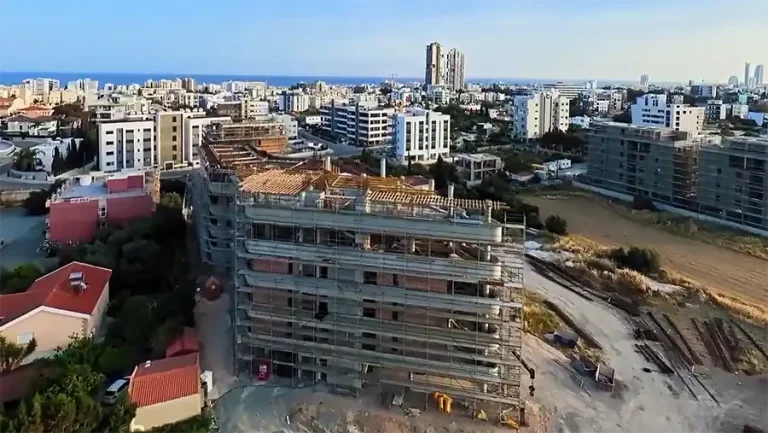
Limassol continues to experience a period of intense construction activity, with local authorities processing a record number of planning and building permit applications while also tackling the growing issue of unsafe buildings across the district.

According to Socrates Metaxas, Director General of the Limassol District Local Government Organisation (DGLO), around 1,000 new applications for planning and building permits are being submitted every month, highlighting the strength of development activity throughout the district.

Apartment blocks lead development in Limassol

Speaking to local media, Mr Metaxas said the organisation inherited approximately 8,500 outstanding cases when it was established on 1 July 2024. Around two-thirds of those applications have now been processed, while officials continue to assess new submissions arriving daily.

“Our objective is to clear all inherited pending cases by the end of this year so that we can operate under fully normal conditions,” he said.

Despite geopolitical tensions in the wider region, Limassol’s development momentum remains strong. Mr Metaxas noted that application volumes show no signs of slowing, with the majority relating to apartment buildings, including several high-rise residential projects and towers.

He explained that Limassol differs from other districts due to the large buildable floor area included in approved applications, largely driven by the presence of tall buildings. Most development activity is concentrated within the wider urban area stretching from Moni and Parekklisia to Episkopi.

Growing interest in high-rise coastal projects

Interest in high-rise developments remains strong, with several applications already submitted and others currently being prepared.

Mr Metaxas said authorities are working to assess proposals within the framework established by the Department of Town Planning and Housing and the relevant local municipalities, ensuring that broader planning principles are maintained.

He stressed that no area in Limassol has been designated exclusively for tall buildings. Instead, each application is assessed according to planning legislation, infrastructure capacity and the characteristics of the surrounding area.

Particular attention is being focused on Aktaias street, where further applications for high-rise developments are expected. Property owners have already expressed interest in pursuing additional tower projects in the area.

Meanwhile, staffing levels at the DLGO continue to increase. The organisation is expected to employ around 500 people by the end of the year, with efforts focused on training and integrating new staff into operations.

Warning over nearly 1,000 unsafe buildings

Alongside the construction boom, authorities are facing a significant challenge involving dangerous and unsafe buildings throughout the district.

Mr Metaxas revealed that around 1,000 unsafe buildings have now been identified across Limassol. The organisation initially inherited responsibility for approximately 700 from previous authorities, but ongoing inspections have increased that figure substantially.

Of particular concern are around 40 buildings classified as highly dangerous and requiring immediate intervention.

However, Mr Metaxas argued that current legislation does not provide all the tools needed for swift enforcement action. Existing powers do not fully allow authorities to disconnect utility services such as electricity and water or to enforce immediate evacuations where necessary.

He emphasised that responsibility for maintaining buildings remains primarily with property owners. Ideally, he said, authorities should have the legal ability to enter and secure unsafe premises immediately, regardless of objections from owners.

As Limassol’s skyline continues to evolve, officials face the dual challenge of supporting economic growth through new development while safeguarding residents from ageing and potentially hazardous buildings.

The DGLO says it remains committed to meeting the city’s growing needs, improving public services and supporting the continued development of Limassol’s economy.

Cypriot buyers shift to smaller apartments as prices rise

The dominance of new-build developments across Cyprus is reshaping buyer behaviour, with increasing numbers of local purchasers opting for smaller apartments in an effort to secure affordable housing.

Industry figures argue that the market currently offers a wide range of available properties and reject claims of a widespread housing shortage. They also note that recent geopolitical tensions, despite causing an initial slowdown, have ultimately reinforced demand across the property sector.

Latest figures from the Department of Lands and Surveys highlight the market’s resilience. During the first quarter of 2026, property sale contracts increased by 14% year-on-year, while total transactions reached 4,079.

Strong supply supports market activity

Speaking to StockWatch, Cyfield Group chief executive George Chrysochos said the market recovered quickly following the initial uncertainty caused by regional conflicts and flight restrictions affecting several Arab countries.

“Despite the first reaction to the war and the suspension of flights from Arab countries, the market returned rapidly, resulting in higher transaction levels than last year,” he said.

According to Mr Chrysochos, the supply of available properties has expanded significantly, creating a healthier balance between supply and demand and offering more opportunities for prospective buyers.

He added that increased housing supply has also helped stabilise rents after several years of steep increases.

However, prices for new-build homes continue to rise, driven largely by construction costs and escalating land values.

In Limassol, land prices remain under pressure due to the limited availability of development plots and the arrival of major investors from neighbouring countries undertaking large-scale projects.

Developers are also facing higher costs linked to global supply chains, transport, shipping and labour shortages. These factors have pushed construction costs higher, leading to annual price increases of between 5% and 10% for new-build properties in Limassol.

Property values in the city continue to vary significantly according to proximity to the coastline. Seafront developments typically command between €8,000 and €15,000 per square metre, while conventional apartments located inland near or above the motorway generally average around €4,000 per square metre.

In contrast, Nicosia remains considerably more affordable for local buyers. A typical two-bedroom apartment in Latsia currently sells for between €220,000 and €230,000. With bank financing covering up to 80% of the purchase price, buyers generally require a deposit of between €40,000 and €50,000.

Rental pressures continue across regional markets

Estate agent Vassos Zannetos said a large number of modern residential developments have entered the Larnaca market, but the rental levels sought by landlords remain beyond the reach of many local residents.

A two-bedroom apartment within the city typically commands rents of €1,000 per month or more, while three-bedroom properties often exceed €2,000 per month. Properties in surrounding areas are generally only around €100 cheaper.

Mr Zannetos highlighted a severe shortage of affordable rental homes in the €600 to €800 monthly range, noting that long-term tenants are reluctant to leave existing properties due to significantly higher rents elsewhere.

Purchase prices in and around Larnaca also remain elevated. Two-bedroom apartments generally start at €240,000, while three-bedroom homes frequently exceed €400,000. Strong demand continues to support pricing, with developers showing little willingness to reduce asking prices.

Affordability challenges are increasingly affecting Cypriot buyers, with rising property values spreading beyond urban centres into suburban and rural communities.

Kiti remains a popular and well-organised residential area, where two-bedroom apartments are priced at around €200,000 and three-bedroom units start from approximately €280,000.

Meanwhile, Alethriko has emerged as an increasingly attractive alternative for buyers seeking better value within easy reach of Larnaca. Mr Zannetos believes developers should place greater emphasis on projects aimed at local buyers, allowing two-bedroom homes to be offered closer to the €190,000 mark.

Foreign demand continues to drive prices higher

In Paphos, estate agent George Petrou said rental supply remains extremely limited, particularly for one-bedroom apartments.

He argued that both rental and sales markets are increasingly targeting foreign buyers rather than local households. Monthly rents for two-bedroom apartments typically start from €800, while three-bedroom properties generally exceed €1,200.

Mr Petrou said demand from Israeli buyers remains strong, particularly for land and residential properties. He also believes ongoing instability in the Middle East is encouraging more investors from the region, especially from Dubai, to view Cyprus as a safe investment destination.

For local buyers, however, affordability has become a growing concern.

“Three years ago, someone could purchase a building plot for €200,000. That is no longer possible,” he said.

According to Mr Petrou, many Cypriots are searching for homes priced around €300,000, yet even at that level buyers often struggle to secure anything other than older resale properties.

George Mouskides, director of Fox Smart Estate Agency and a member of the Property Owners Association, said the market began normalising in 2023 but is now experiencing unprecedented levels of apartment construction.

The surge in new developments has helped place downward pressure on rents, although he expects rental values to stabilise at current levels over time.

Mr Mouskides estimates that rising demand and higher raw material costs linked to global conflicts have pushed property prices up by around 10% across all major Cypriot cities.

He also noted a clear shift in purchasing habits, with local buyers increasingly favouring smaller and more affordable apartments or turning to older resale properties that offer larger living spaces at lower prices.

Despite affordability concerns, buyers are not postponing purchases.

“People know that prices rise every year, so they continue to buy,” he said.

Current market pricing places one-bedroom apartments at around €170,000, two-bedroom units at approximately €270,000 and three-bedroom properties at around €320,000.

Two-bedroom apartments remain the most popular choice among purchasers, while one-bedroom units dominate the rental market, followed by two-bedroom properties.

Conclusion

Cyprus’ residential property market continues to demonstrate strong momentum, supported by robust demand, expanding new-build supply and sustained foreign investment.

Yet while developers are delivering more homes than ever before, rising construction costs and growing international demand continue to challenge affordability for local buyers. As a result, smaller apartments and selected resale properties are increasingly becoming the preferred route onto the housing ladder for many Cypriot households.

Cyprus property sales post 5 per cent growth in May

Cyprus’ property market continued its upward momentum in May, with property sales continuing to rise despite weaker activity in two districts.

Official figures released by the Department of Lands and Surveys show that 1,723 property sale contracts were deposited at Land Registry offices across the island during May 2026. This represents a 5% increase compared with the 1,644 contracts recorded in May 2025.

The figures cover all segments of the real estate market, including residential properties such as houses and apartments, commercial assets including offices, retail premises and warehouses, as well as land transactions involving building plots and agricultural fields.

While property sales declined in Nicosia and Famagusta, strong performances in other districts more than offset the losses. Sales in Nicosia fell by 12%, while Famagusta recorded an 8% decrease year-on-year.

In contrast, Paphos delivered the strongest growth, with property sales climbing by 24% compared with May last year. Larnaca also reported a solid increase of 14%, while Limassol recorded growth of 2%

Total contracts of sale deposited – 2025/2026 Comparison (May)

Property sales continue to rise in 2026

The positive trend has been evident throughout the year. During the first five months of 2026, a total of 8,043 property sale contracts were deposited at Land Registry offices across Cyprus.

This marks a 12% increase on the 7,185 contracts recorded during the same period in 2025, with every district reporting year-on-year growth.

Limassol remained the island’s busiest property market, recording 2,537 sales contracts between January and May. Nicosia followed with 1,749 transactions, narrowly ahead of Larnaca with 1,747. Paphos recorded 1,631 sales, while Famagusta accounted for 379 transactions.

Total contracts of sale deposited – 2025/2026 Year-to-Date Comparison


The latest figures underline the continued resilience of the Cyprus property market, with demand remaining strong across key residential, commercial and land sectors despite regional variations in activity.